
Oregon medical professionals face daily liability risks. A single claim can threaten your practice, your finances, and your career. This is why medical malpractice liability insurance isn’t optional; it’s essential.
At ABI Insurance, we’ve helped countless Oregon healthcare providers understand their coverage options and protect what they’ve built. This guide walks you through Oregon’s specific requirements, how to assess your risk, and how to choose a policy that fits your practice.
What Medical Malpractice Insurance Actually Covers
Medical malpractice liability insurance protects you when a patient claims you failed to provide the standard of care expected in your specialty, and that care resulted in harm. The policy covers legal defense costs, settlements, and damages awarded by a court or jury. In Oregon, this protection matters because patients can file claims up to two years after discovering an injury, with a five-year absolute deadline from the date of treatment. Over 30% of U.S. physicians face a malpractice claim at some point in their careers, and when claims happen, they’re expensive. The average medical malpractice payout in 2025 was $496,232 per claim, according to the National Practitioner Data Bank data. Without insurance, you’d be personally liable for these costs, which could wipe out your savings, future earnings, and practice assets.
Claims arise from routine situations
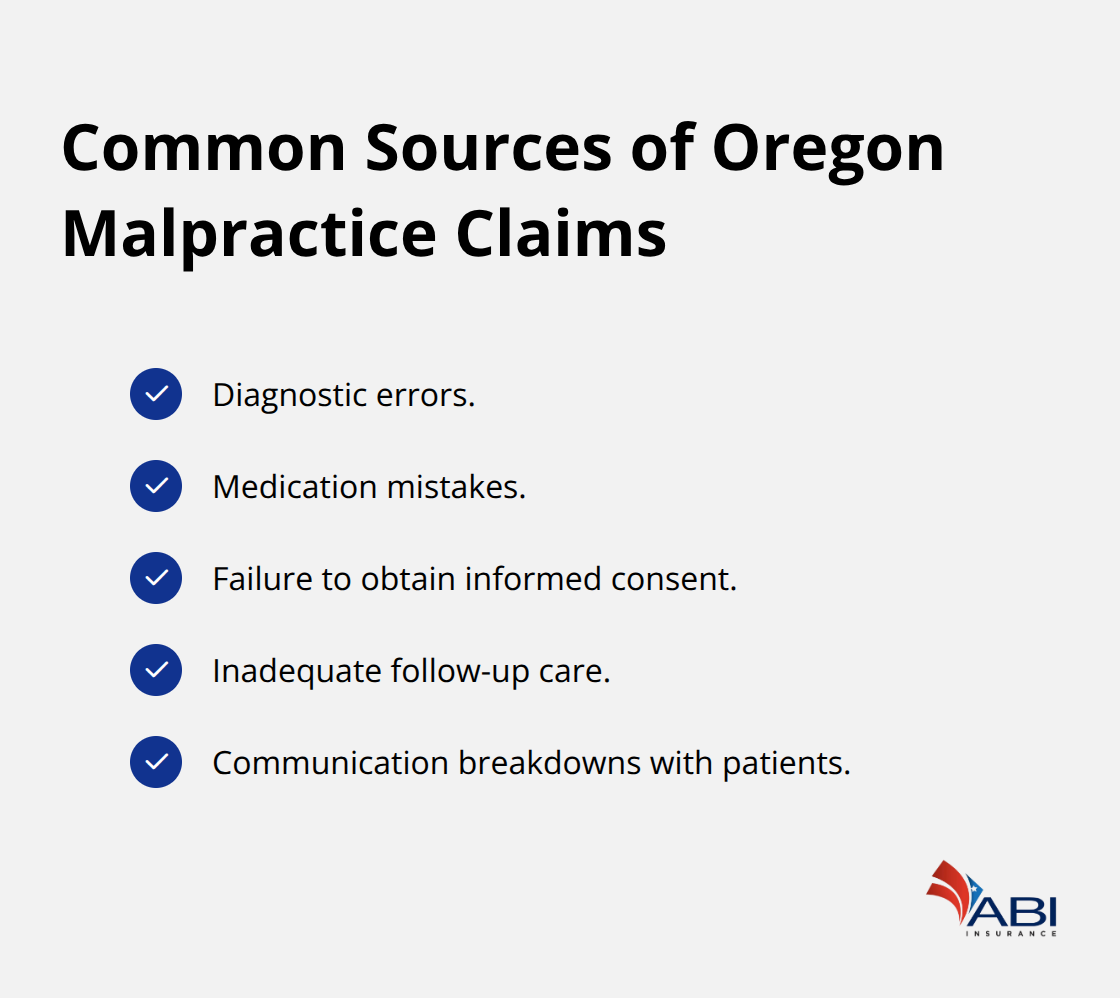
You might think malpractice claims only occur from catastrophic surgical errors, but Oregon’s claims data tells a different story. In 2025 alone, Oregon experienced about 112 medical malpractice payouts, totaling over $55 million. Claims arise from diagnostic errors, medication mistakes, failure to obtain informed consent, inadequate follow-up care, and communication breakdowns with patients.
A family medicine physician might face a claim because they missed an early cancer diagnosis. An emergency medicine physician might be sued for misreading imaging or not recognizing sepsis. Even low-risk specialties like psychiatry and dermatology generate claims. The point is this: claims don’t discriminate by specialty or how careful you think you are. Insurance covers you when they happen.
Occurrence and claims-made policies work differently
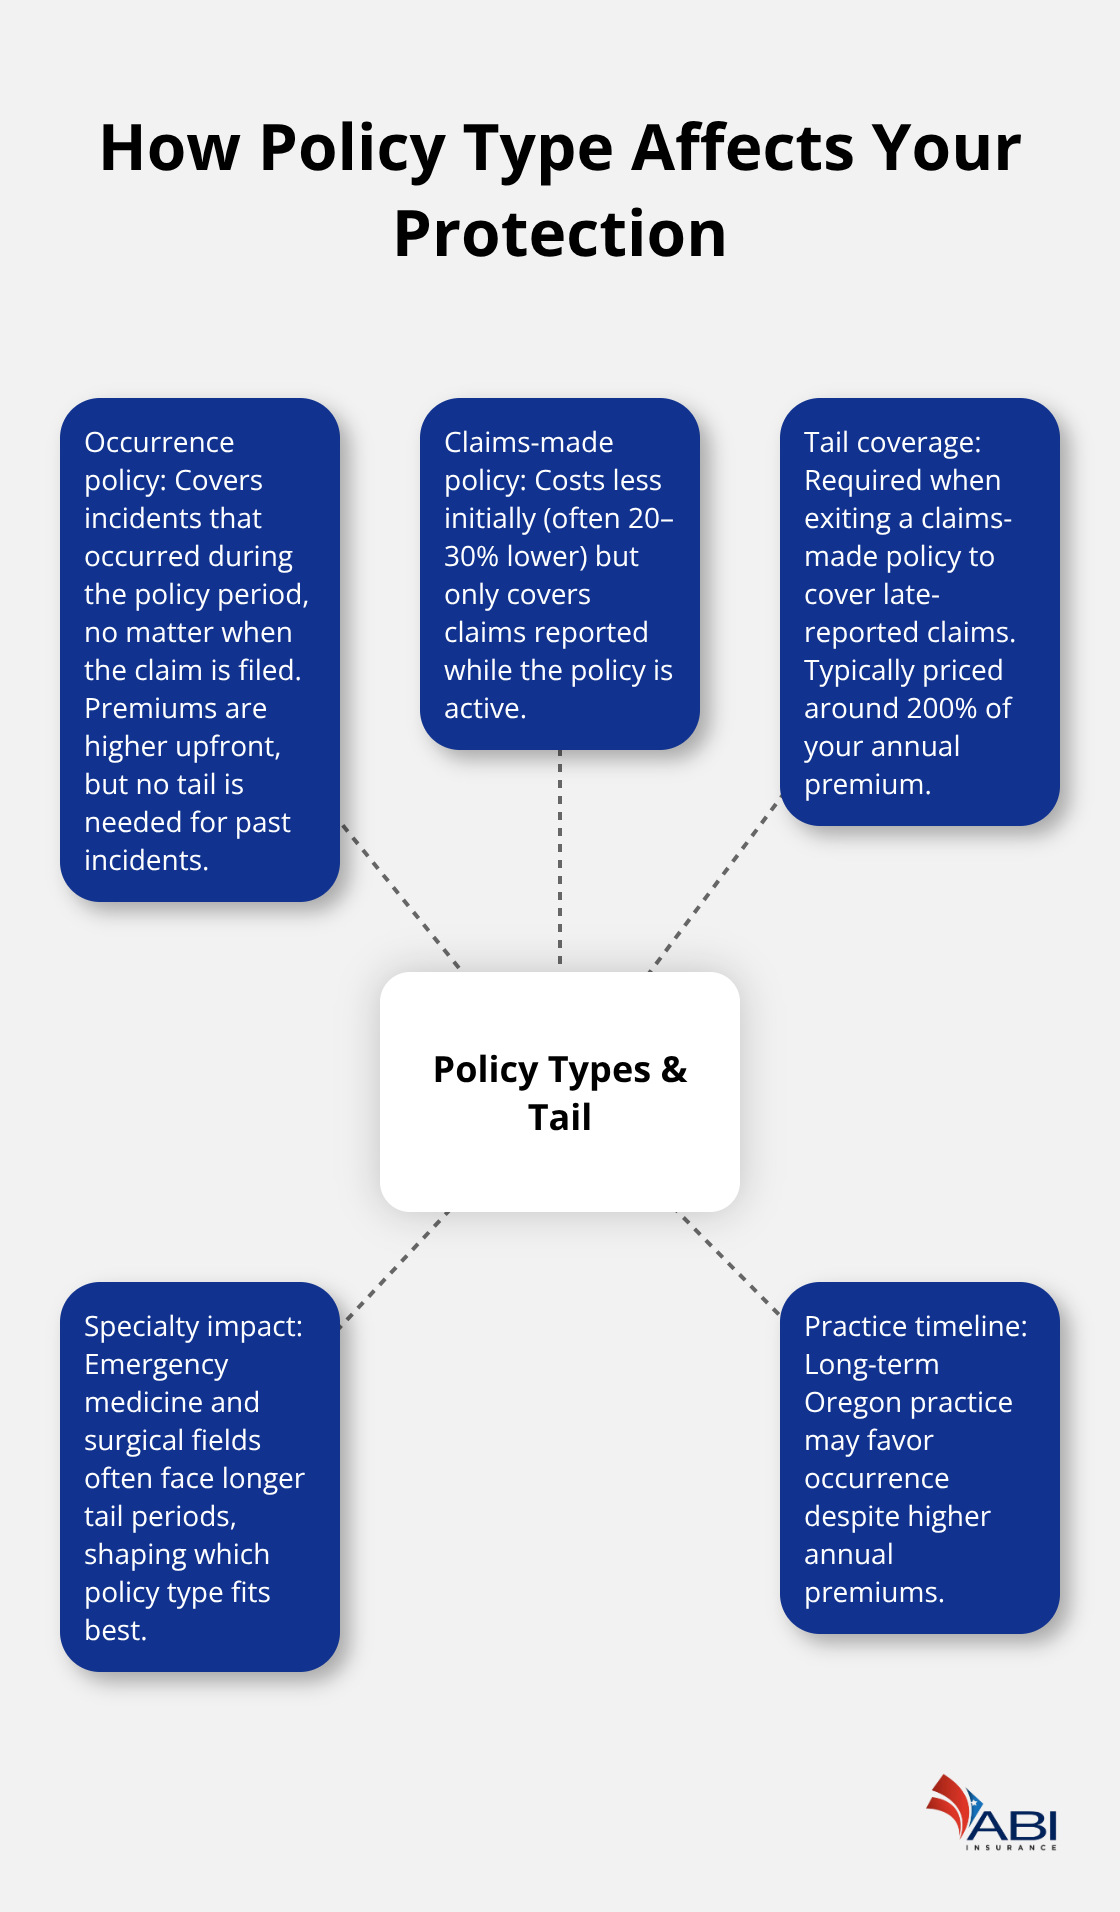
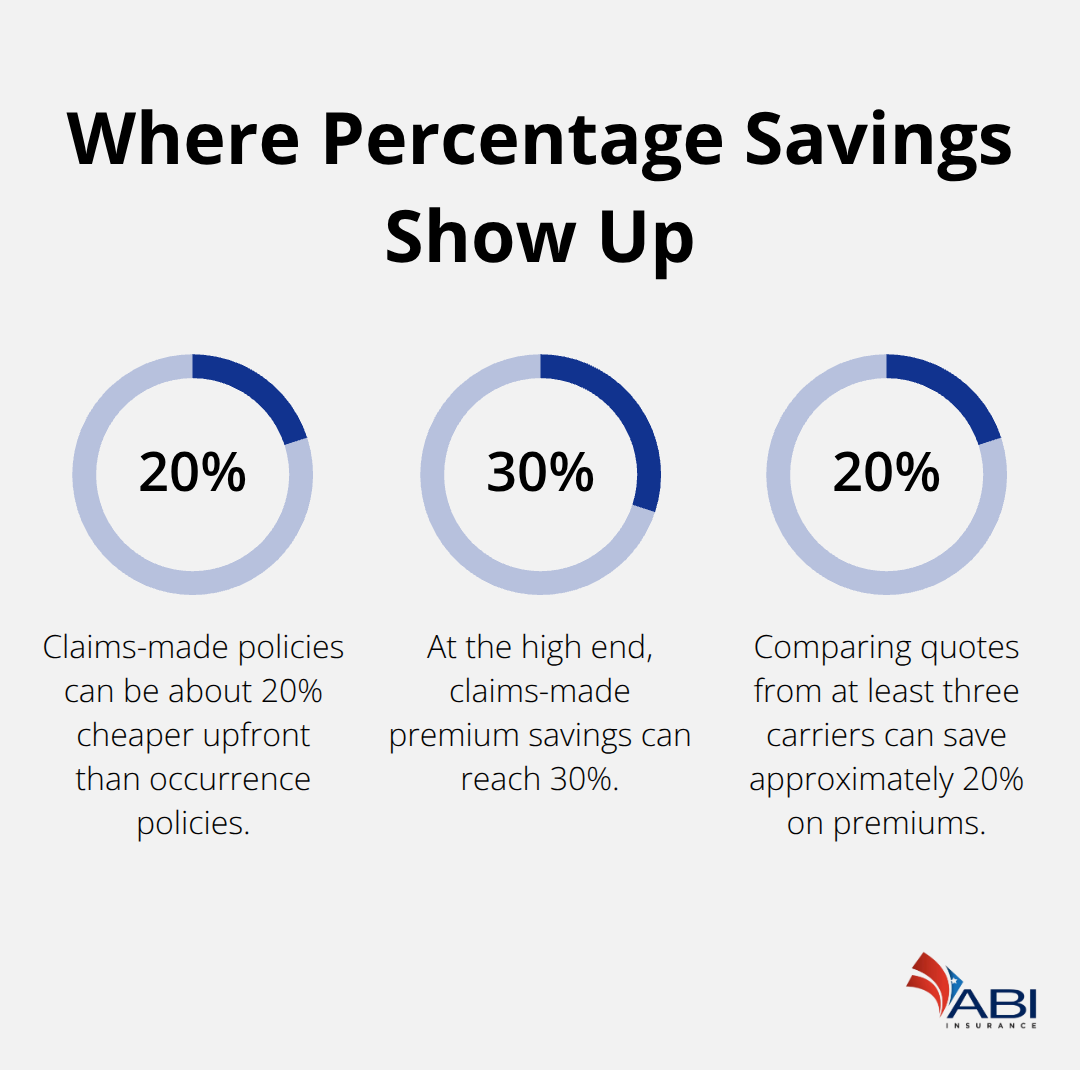
An occurrence policy covers claims for incidents that happened during the policy period, regardless of when the claim is filed. You pay higher premiums upfront, but once the policy expires, you’re protected forever for those past incidents. A claims-made policy is cheaper initially, often by 20 to 30%, but it only covers claims reported while the policy is active. When you leave a claims-made policy — whether you’re retiring, changing jobs, or switching carriers — you need tail coverage to protect yourself against claims filed after you exit. Tail coverage typically costs around 150-200% of your annual premium and extends protection back to a specified date.
Your specialty determines which option makes sense
If you practice emergency medicine, where claims often surface years after the incident, tail coverage becomes essential. For surgeons and high-risk specialties, the upfront savings of a claims-made policy often don’t justify the tail costs you’ll face later. Oregon physicians should factor in their specialty’s claim timeline when choosing between these options. This assessment directly influences your next decision: determining what coverage limits your practice needs.
What Oregon Law Requires You to Know
Oregon’s Insurance Mandate: The Reality Behind the Law
Oregon doesn’t legally mandate that you carry medical malpractice insurance, but that distinction matters far less than you’d think. Most hospitals, surgery centers, and credentialing boards require proof of coverage as a condition for granting privileges or participating in their networks. You’ll encounter this requirement quickly when you apply for hospital privileges or join a medical group. The state defines your standard of care through Oregon Revised Statutes 677.095(1), which holds you to the care, skill, and diligence used by ordinarily careful physicians in similar circumstances in your community.
The Four Elements Patients Must Prove
When a patient sues, they must prove four elements: that you had a duty of care, breached that duty, caused harm through that breach, and resulted in measurable damages. This framework shapes what insurers will defend and how juries evaluate claims. Oregon’s two-year statute of limitations runs from discovery of the injury, not from the date of treatment, and a five-year absolute repose deadline applies regardless of when you discover the harm. A claim filed on day 1,826 after treatment gets dismissed. This timeline is strict and unforgiving.
Coverage Limits Determine Your Personal Liability
Your malpractice insurance covers legal defense costs and damages, but the policy limits you choose determine your actual protection. If a jury awards $1 million in damages and your policy limit is $500,000, you’re personally liable for the remaining $500,000. Oregon imposes no cap on economic damages like medical expenses and lost wages, which means large claims happen regularly. Non-economic damages in wrongful death cases are capped at $500,000, but individual physicians cannot face punitive damages under state law, though hospitals and health systems can.
Specialty and Facility Requirements Shape Your Coverage Needs
Coverage minimums vary dramatically by specialty and facility. A typical hospital requirement for visiting privileges is $200,000 per claim and $600,000 annual aggregate, but many facilities demand higher limits. Family medicine physicians without surgery average around $7,684 annually for $1 million per claim coverage according to state-filed rate data, while emergency medicine physicians pay roughly $16,873 on average. Surgeons face steeper costs: general surgery averages $29,088, and obstetrics/gynecology major surgery reaches $39,881 annually. Orthopedic surgeons without spine procedures average $22,464.
These are benchmarks; actual premiums vary by county, your claims history, and the carrier. Oregon’s soft insurance market means competition keeps rates competitive, and experienced brokers can negotiate discounts up to 50% off published rates. Your specialty’s risk profile determines your needs more than facility minimums do. Emergency medicine and surgery claim patterns differ fundamentally from psychiatry or radiology, which influences both premium costs and tail coverage decisions.
How Oregon Compares to Other States
Compared to other states, Oregon’s lack of tort reform and the absence of a general damages cap create a higher claims environment than states with damage caps or mandatory arbitration. However, Oregon’s modified comparative negligence rule limits recovery if the plaintiff is more than 50% at fault, which provides some defense protection. This legal landscape shapes your coverage strategy. Assess your specialty’s actual claims frequency, your facility’s specific requirements, and your personal risk tolerance before selecting limits. Underinsuring creates personal liability exposure that could follow you for years, which is why choosing the right policy requires understanding not just what the law allows, but what your practice demands.
Choosing the Right Coverage for Your Oregon Practice
Match Your Coverage Limits to Your Specialty’s Risk Profile
Your specialty’s risk profile should drive your coverage decision, not facility minimums or generic benchmarks. Emergency medicine physicians face fundamentally different claim patterns than family medicine practitioners, which means your limits need to reflect your actual exposure. Start by examining your specialty’s payout data. In 2025, Oregon saw about 112 medical malpractice payouts across the state, totaling over $55 million according to the National Practitioner Data Bank. However, averages mask critical variation. Obstetrics/gynecology major surgery claims in Oregon average around $39,881 annually in premiums for $1 million per claim coverage, while psychiatry averages $5,822 —a sevenfold difference. Emergency medicine sits at roughly $16,873 annually. This disparity exists because surgical specialties produce higher severity claims with longer tail periods.
When you assess your risk, pull your own claims history and compare it against your specialty’s baseline. If you’ve practiced for ten years without a claim in a high-risk specialty like surgery, your profile differs from someone with one previous claim. Carriers weigh this heavily when underwriting. Request a detailed loss history report from the National Practitioner Data Bank before shopping for coverage; this document shows whether any prior claims exist under your name and helps you understand what insurers will discover during their investigation.
Set Limits That Protect Your Personal Assets
Coverage limits require a different calculus than premiums alone. Your facility likely mandates $200,000 per claim and $600,000 annual aggregate as a baseline, but these minimums protect the hospital, not your personal assets. A single claim exceeding these limits leaves you personally liable for the difference. Oregon imposes no cap on economic damages, which means a surgical complication resulting in permanent disability can produce awards well above $1 million when you factor in lost wages, ongoing medical care, and household services. The National Practitioner Data Bank shows that payouts regularly exceed facility minimums, particularly in high-risk specialties.
Consider your personal net worth, your practice structure, and your specialty’s actual claim severity when setting limits. Most surgeons should carry at least $1 million per claim and $3 million annual aggregate; emergency medicine physicians should do the same given claim frequency and severity. Radiologists and psychiatrists might adequately cover their exposure with $1 million per claim and $2 million annual aggregate, though this depends on your facility’s requirements and your county’s litigation environment.
Evaluate Claims-Made Versus Occurrence Coverage
Once you’ve determined appropriate limits, evaluate whether claims-made and occurrence coverage fits your long-term practice plans. Claims-made policies cost 20 to 30% less upfront but require tail coverage when you exit, which runs approximately 150-200% of your final annual premium. An emergency medicine physician paying $31,620 annually faces a tail bill of roughly $63,240 upon retirement. Occurrence policies cost more initially but eliminate this future expense. If you plan to practice in Oregon for twenty-plus years, occurrence coverage often proves more economical despite higher annual premiums.
Compare Carriers and Negotiate Terms
When comparing carriers, prioritize AM Best A-rated insurers like The Doctors Company and MedPro Group. These carriers have demonstrated financial strength and claims handling expertise. Evaluate each carrier’s defense strategy, settlement authority, and tail coverage terms.
Some carriers offer consent-to-settle clauses that require your approval before settling a claim, which protects your reputation but could also prolong litigation. Others settle more aggressively to minimize legal costs. Your specialty and personality determine which approach matters more.
Final Thoughts
Medical malpractice liability insurance protects your practice, your finances, and your career. Your specialty’s risk profile must drive every decision you make. Oregon saw about 112 medical malpractice payouts in 2025 totaling over $55 million. Start by pulling your claims history from the National Practitioner Data Bank. Evaluate whether claims-made or occurrence coverage fits your long-term practice plans, since claims-made policies cost less upfront but require tail coverage when you exit (roughly 150-200% of your annual premium), while occurrence policies cost more initially but eliminate this future expense. Your practice timeline and personal risk tolerance determine which option makes financial sense for your situation. A multi-carrier comparison can save approximately 20% on premiums and reveal meaningful differences in claims support and premium flexibility that matter far more than price alone.
Contact ABI Insurance to discuss your medical malpractice liability insurance options and secure protection that fits your practice. We help Oregon medical professionals navigate these decisions with personalized guidance tailored to your specialty and practice structure. Don’t wait until a claim surfaces to realize your coverage was inadequate.


 Doctor Medical Liability Insurance: Protecting Oregon Physicians









