
Your homeowners and auto insurance policies have limits. When a lawsuit exceeds those limits, your personal assets are at risk.
An umbrella policy for families fills that gap by providing additional liability coverage that protects your savings, home equity, and future earnings. At ABI Insurance, we see families overlook this protection until it’s too late. This guide explains what umbrella insurance covers, why your family needs it, and how to choose the right amount of protection.
What an Umbrella Policy Covers
An umbrella policy provides additional liability coverage that activates when your homeowners or auto insurance reaches its limit. An umbrella policy covers any portion of a lawsuit judgment that exceeds your standard insurance limits. Standard homeowners insurance typically caps liability at $100,000 to $300,000, while auto policies often max out at $250,000 to $500,000. These limits sound substantial until you face a serious accident. A single lawsuit from a severe injury can easily reach $1 million or more. Personal injury lawsuit settlements can be substantial, making umbrella coverage essential for most households.
How the Coverage Layer Works
Your umbrella policy sits directly above your existing homeowners and auto insurance. It doesn’t replace those policies; it extends them. Think of it as additional protection that kicks in when your primary policies are exhausted. If you carry a $300,000 homeowners policy and purchase a $1 million umbrella policy, you’re protected up to $1.3 million total. Most insurers require you to maintain minimum underlying coverage before they’ll sell you an umbrella policy, typically $250,000 on homeowners and $250,000 per person on auto.
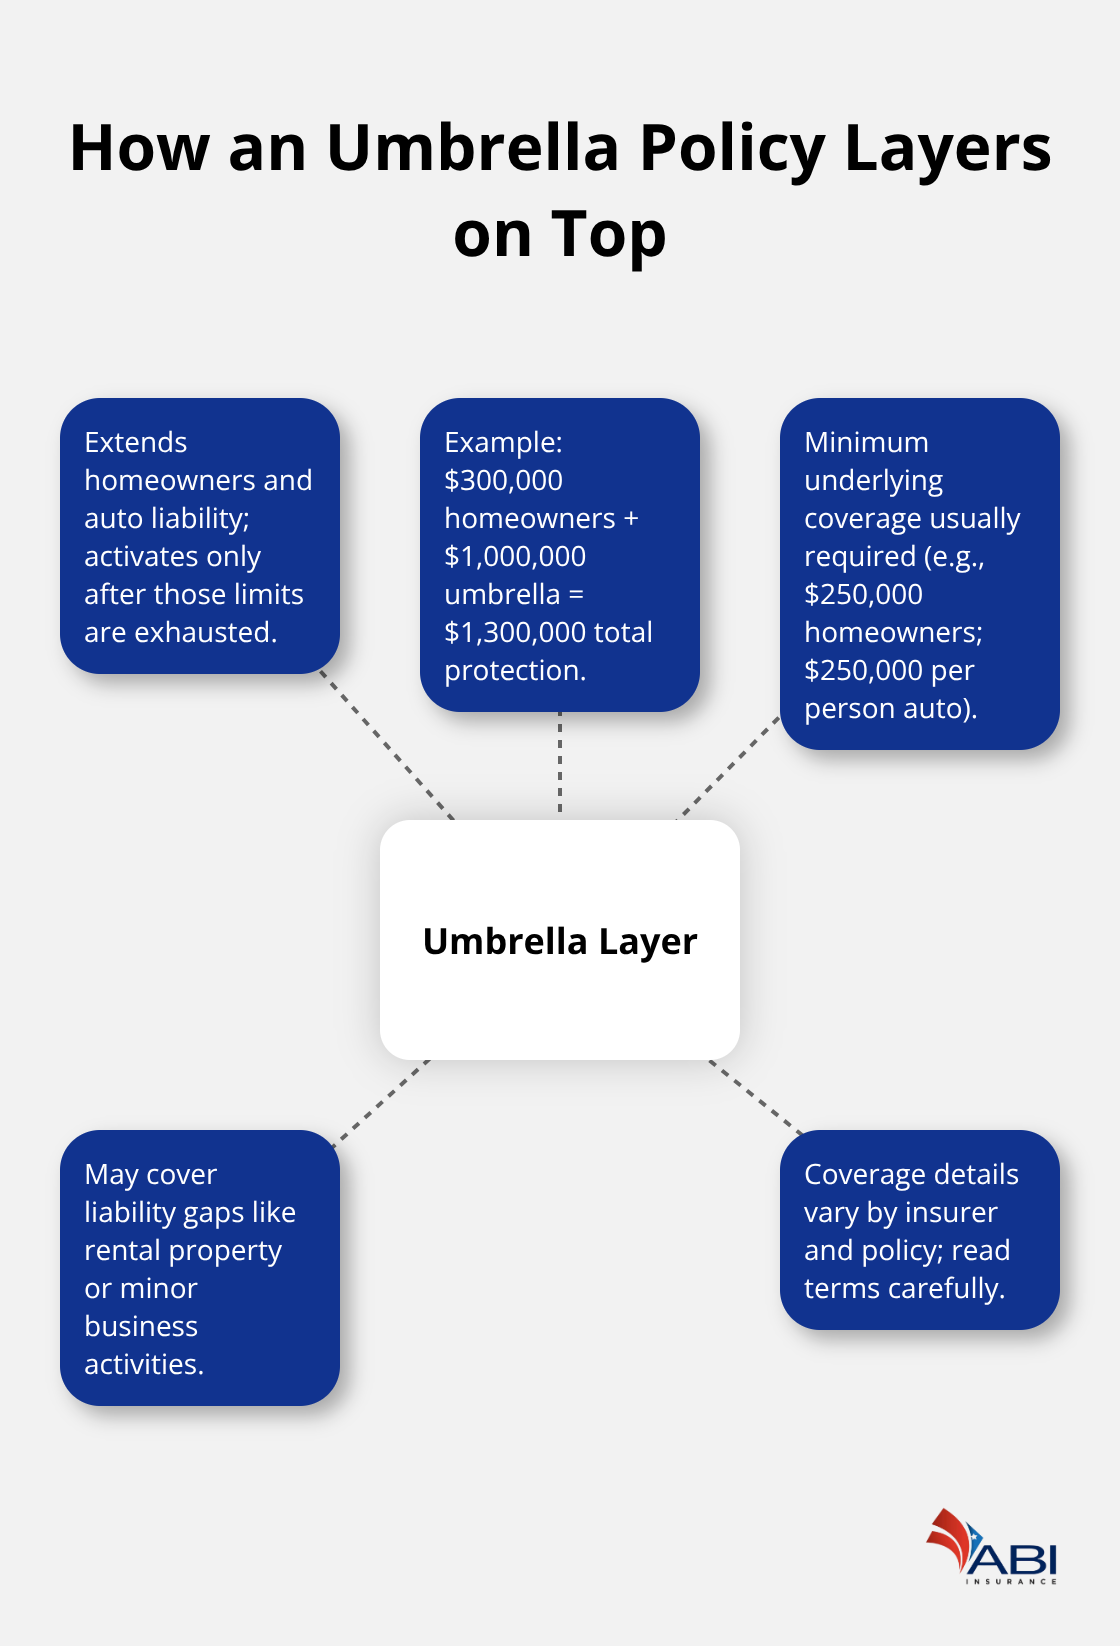
This requirement protects the insurance company and confirms you have adequate base coverage. Umbrella policies also cover certain liability gaps that standard policies exclude, such as rental property liability or minor business activities (though coverage varies by policy).
Calculating Your Net Worth and Assets
The right umbrella limit depends on your household’s assets and income. Start by calculating your net worth. Add up your home equity, savings, investments, and retirement accounts. If your net worth is $500,000, a $1 million umbrella policy provides reasonable protection. Households with $1 million or more in assets should seriously consider $2 million in umbrella coverage. Your future earning potential matters too. If you’re a high-income earner with decades of working years ahead, a larger umbrella limit protects your future wages from garnishment in a major lawsuit settlement.
Understanding Umbrella Policy Costs
Umbrella coverage costs remain remarkably affordable. A $1 million umbrella policy typically runs $200 to $400 annually, while $2 million in coverage averages $400 to $600 per year. This affordability makes it difficult to justify going without protection. Most families find that the annual premium represents a small fraction of their net worth, yet the protection covers potential losses that could devastate their financial future. The low cost-to-benefit ratio explains why umbrella policies have become standard for households with substantial assets.
Protecting Future Income and Assets
Your umbrella policy protects more than your current savings; it shields your future earning potential. A major lawsuit settlement can result in wage garnishment that lasts years or even decades. Courts can garnish a portion of your income to satisfy a judgment, which means your future paychecks become vulnerable without adequate umbrella coverage. This protection becomes especially important if you have children who depend on your income or if you’re building wealth through your career. The umbrella policy stands between your family’s financial security and a catastrophic liability claim that could otherwise derail your long-term plans.
Why Your Standard Insurance Isn’t Enough
Your homeowners and auto policies have hard limits. Those limits usually fall short of what most families need. A standard homeowners policy caps liability at $100,000 to $300,000. Auto insurance typically maxes out at $250,000 to $500,000 per person. These numbers sound adequate until you face a serious accident. A single injury lawsuit can exceed $1 million in damages. When a court judgment surpasses your policy limits, creditors pursue your savings, home equity, and future wages to satisfy the debt. Standard policies cannot protect you beyond their stated limits, which means you absorb the financial devastation personally.
The Real Cost of Underinsurance
Liability exposure extends far beyond car accidents. A guest slips on your driveway and suffers a permanent spinal injury. Your teenage son injures another player during a sports activity. A contractor working on your home files a lawsuit after an accident on your property. Any of these scenarios can trigger a six- or seven-figure claim. Without umbrella coverage, you become personally liable for the full amount once your primary policies are exhausted. Courts can garnish your wages for years, sometimes decades, to satisfy a judgment. Your home equity becomes vulnerable to liens and forced sale. Retirement accounts and investment portfolios face seizure depending on state law. Financial recovery from such a claim often takes longer than the lawsuit itself, draining resources you intended for your family’s future.
Protecting What You’ve Built
The cost of umbrella insurance is small compared to what it protects. A $1 million umbrella policy runs $200 to $400 annually for most households. A $2 million policy averages $400 to $600 per year. This modest premium shields your accumulated wealth and your future earning potential. High-income earners face particular risk because courts can garnish a larger percentage of their future income. If you earn $150,000 annually with 20 years until retirement, you protect $3 million in potential future earnings through adequate coverage. Your umbrella policy stands between that income stream and creditors seeking to satisfy a judgment. For families with substantial assets or high earning potential, this protection becomes non-negotiable.
Why Coverage Limits Matter More Than You Think
Most households underestimate their actual liability exposure. You might think a $300,000 homeowners limit covers typical accidents, but medical costs for catastrophic injuries have skyrocketed. A severe spinal cord injury can cost $1 million to $4 million over a lifetime in medical care, lost wages, and pain and suffering damages. Courts award these amounts regularly, and your standard policy stops covering the claim long before the verdict is read. Umbrella policies activate when liability limits of underlying policies are exhausted, protecting your family from financial ruin. The gap between what your standard policies cover and what courts actually award represents the real danger to your household’s financial security.
How to Choose the Right Umbrella Coverage for Your Family
Assess Your True Financial Exposure
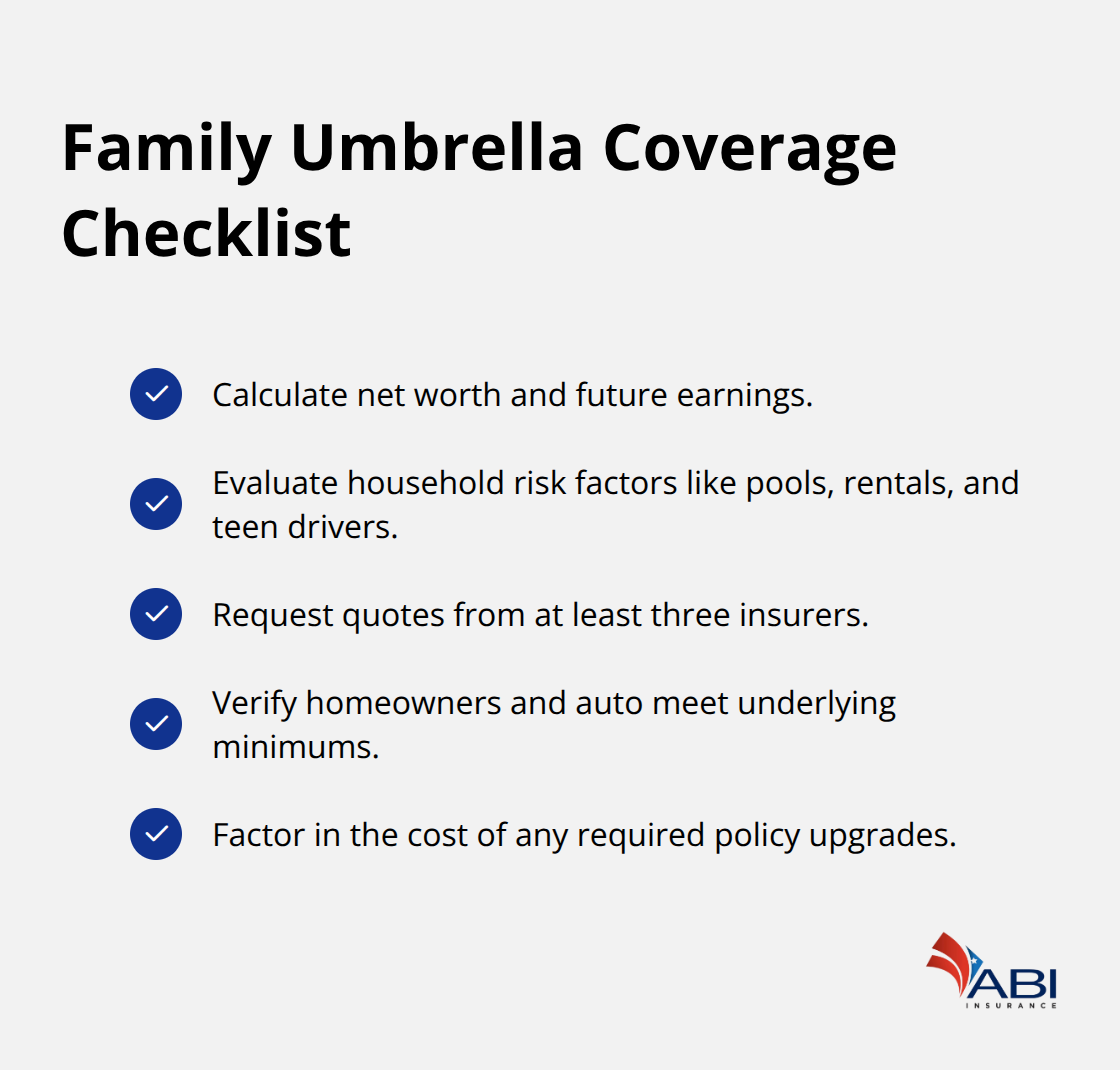
Start with a brutally honest assessment of what you actually own and what you could lose. Most families dramatically underestimate their liability exposure because they focus only on current assets rather than future earning potential. Calculate your net worth by adding home equity, investment accounts, retirement savings, and liquid assets. A household with $600,000 in net worth needs substantially different coverage than one with $2 million.
Next, factor in your annual income and years until retirement. If you earn $120,000 annually and have 25 years of working life remaining, you’re protecting $3 million in potential future wages that creditors could garnish. High-income earners absolutely need higher umbrella limits because courts can garnish a larger percentage of their income to satisfy judgments. Someone earning $200,000 annually faces far greater risk from wage garnishment than someone earning $50,000.
Catastrophic injury settlements can vary widely, from $50,000 to $5 million or more. This gap between awards and coverage can create financial vulnerability.
Evaluate Your Household’s Specific Risk Factors
Your household’s specific activities determine coverage needs. Do you have a swimming pool? Own rental property? Do you host frequent gatherings with guests on your property? Each activity increases liability exposure substantially.
Pools alone trigger significantly higher claims because drowning and injury cases generate massive settlements. Rental properties expose you to tenant injury claims and property damage liability that extends beyond your primary homeowners policy. If you have teenage drivers in the household, your auto liability exposure multiplies with each additional driver.
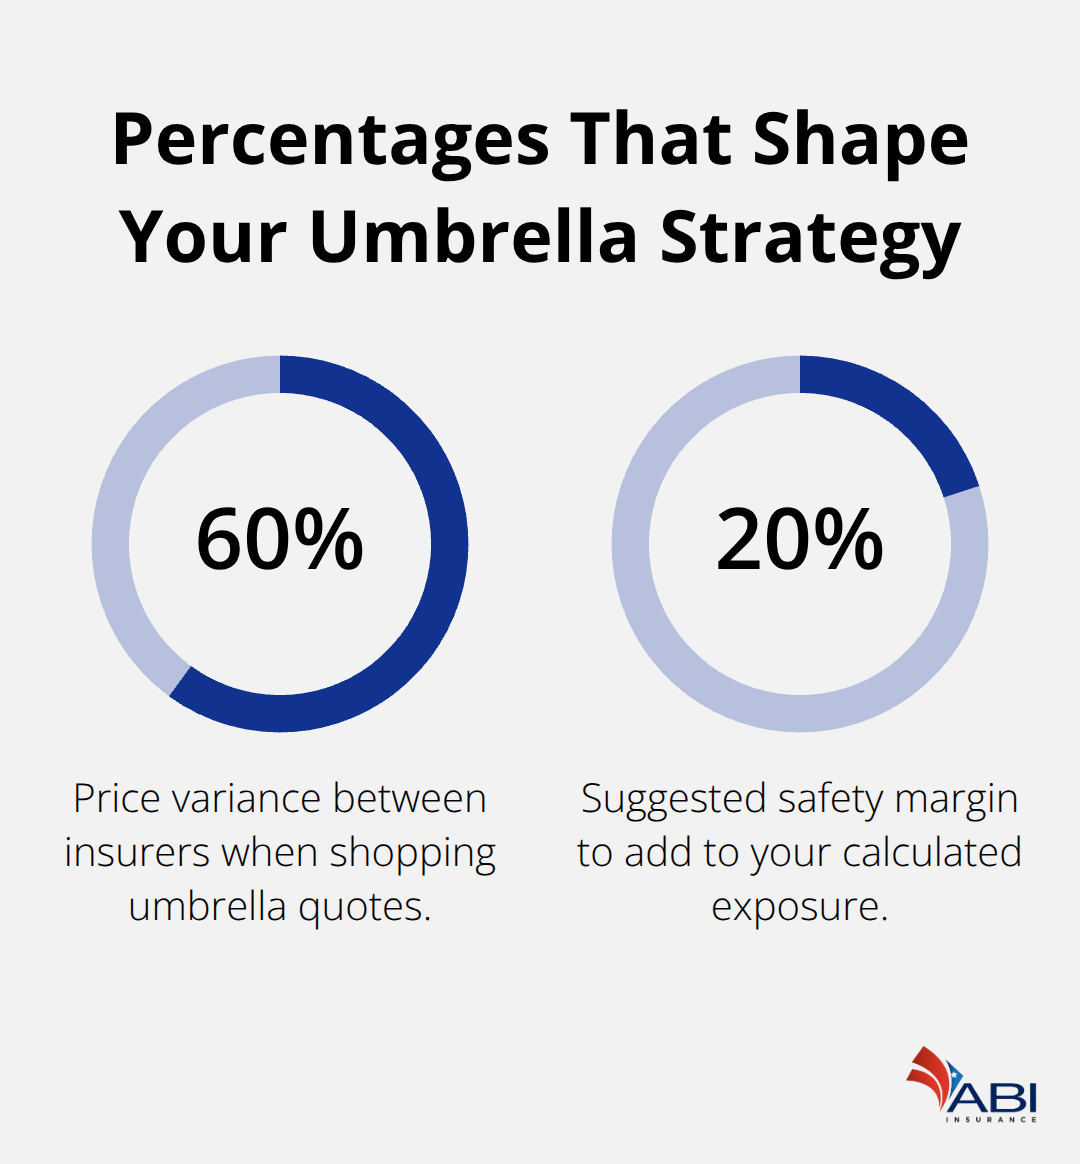
Households with pools, rental properties, or multiple young drivers should carry minimum $2 million umbrella coverage rather than the standard $1 million. Families with young children should also consider that hosting activities creates liability exposure; a child injured during a birthday party or sports activity can trigger a six-figure claim. Once you’ve assessed your specific risk factors, add 20% to your calculated exposure as a safety margin. This buffer accounts for medical cost inflation and the reality that jury awards often exceed initial settlement offers.
Request Quotes
Umbrella pricing varies wildly between insurers. Some charge $250 annually for $1 million coverage while others charge $400 for the identical limit. This 60% price variance means shopping around saves hundreds of dollars annually.
When comparing quotes, verify that each policy requires the same underlying coverage minimums on your homeowners and auto policies. Some insurers demand $300,000 in homeowners liability while others accept $250,000. Lower underlying requirements sometimes indicate weaker coverage terms elsewhere in the policy, so read the details carefully. Rental property liability, business activities, and certain personal liability situations receive different treatment depending on the carrier.
Confirm Your Underlying Policies Meet Minimum Requirements
Before purchasing any umbrella policy, confirm that your homeowners and auto policies meet the insurer’s minimum requirements. Many families discover too late that their existing policies don’t qualify for umbrella coverage, forcing them to upgrade their primary policies first.
An insurer requiring $250,000 in homeowners liability won’t write an umbrella policy if your homeowners coverage maxes out at $200,000. This means you’ll need to increase your homeowners limit, which adds cost beyond the umbrella premium itself. Similarly, auto policies must meet minimum liability limits per person and per accident. If your current auto policy carries $100,000 per person limits, you may need to increase to $250,000 per person to qualify for umbrella coverage.
These upgrades cost money, so factor them into your total protection budget. The good news is that increasing underlying limits typically costs less than you’d expect; raising homeowners liability from $200,000 to $300,000 usually adds $50 to $100 annually. This modest increase opens access to affordable umbrella coverage that protects your entire household.
Final Thoughts
An umbrella policy for families represents the most cost-effective protection you can add to your insurance portfolio. The modest annual premium of $200 to $600 shields assets you’ve spent years building and income you’ll earn over decades. Without this coverage, a single serious accident triggers financial consequences that last longer than the lawsuit itself.
Calculate your net worth and future earning potential to determine your actual liability exposure. Assess your household’s specific risk factors, from pools to rental properties to multiple drivers. Verify that your existing homeowners and auto policies meet the minimum requirements your chosen umbrella carrier demands.
The families who sleep soundly at night aren’t those with the most assets; they’re the ones who’ve taken action to protect what they have. An umbrella policy for families transforms abstract worry into concrete protection. Contact ABI Insurance to discuss your household’s umbrella insurance needs and get started protecting your future.


 Physician Professional Liability Insurance: A Clinician’s Oregon Guide









