
Medical malpractice lawsuits can devastate your practice financially and professionally. Oregon clinicians face real exposure, and clinician medical liability coverage is your primary defense against these risks.
At ABI Insurance, we’ve helped countless practitioners understand what protection they need. This guide walks you through the essentials so you can make informed decisions about your coverage.
What Coverage Actually Protects You
The Core Protection Your Policy Provides
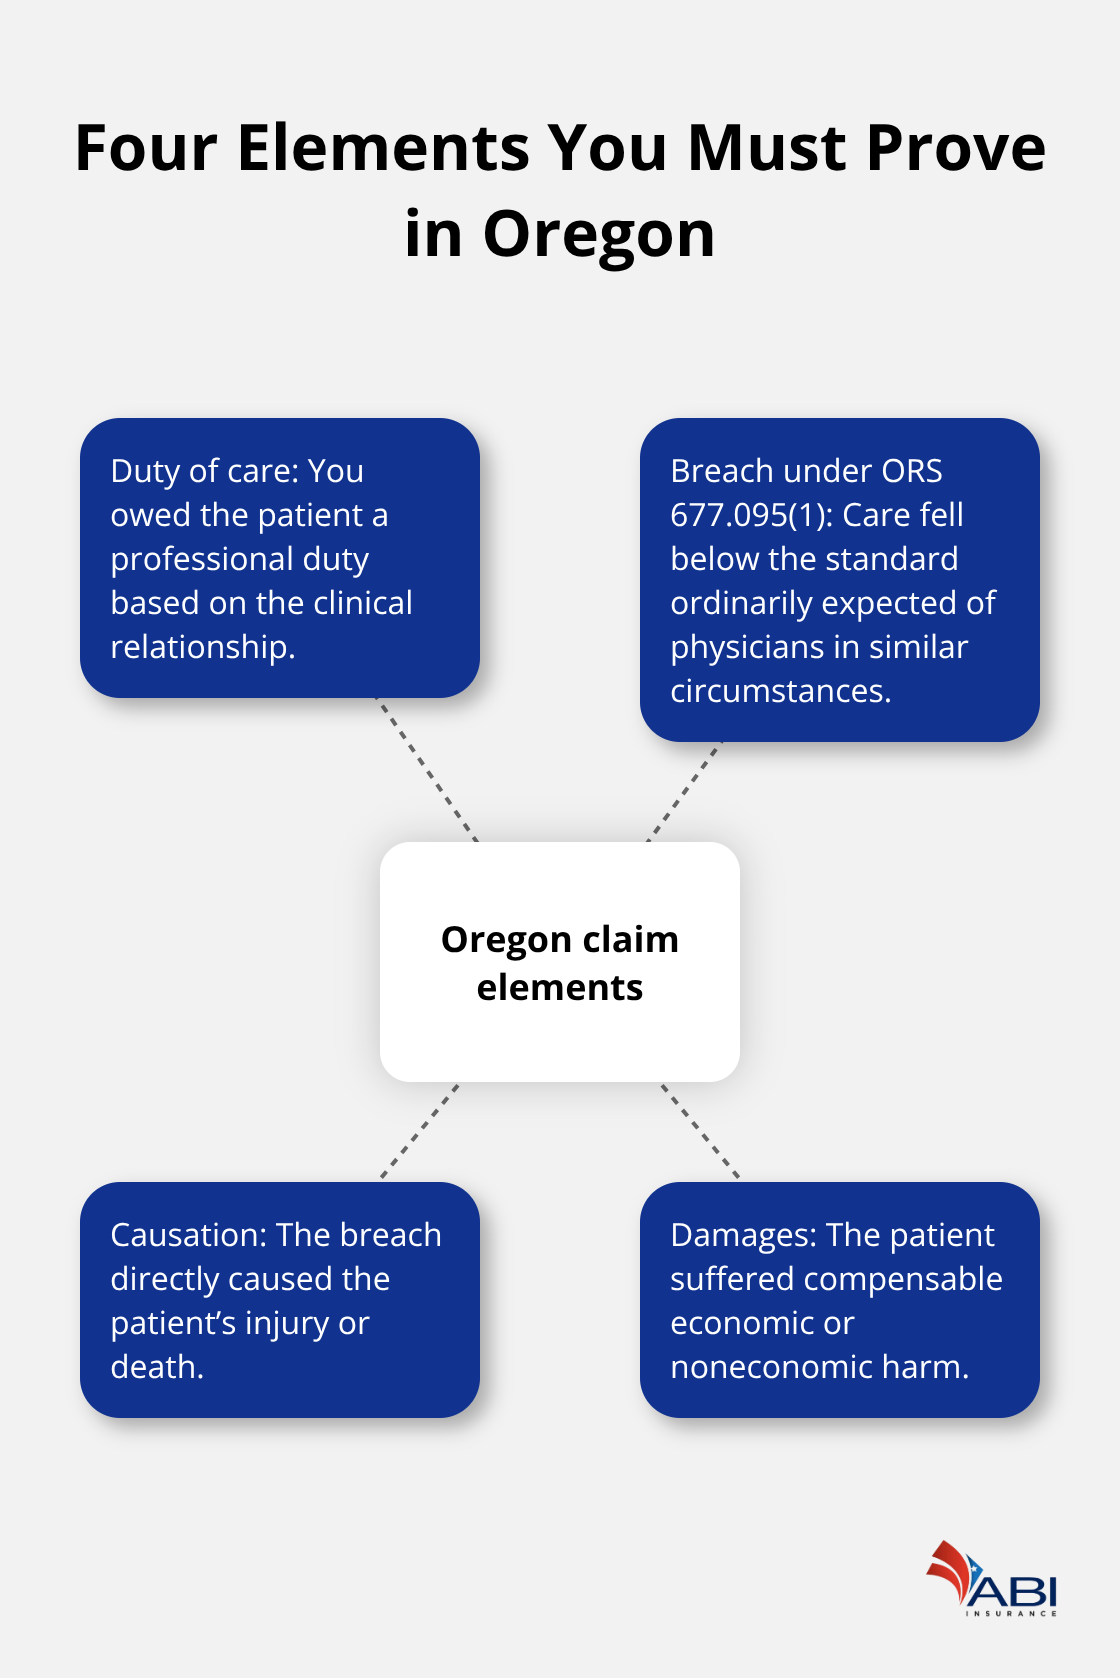
Clinician medical liability coverage protects you when a patient alleges you caused harm through negligence, breach of the standard of care, or wrongful death. The policy covers defense costs — often $150,000 or more in legal fees before trial in complex cases like obstetrics — plus any damages awarded or settled. Oregon requires proof of four elements for a claim to succeed: a duty of care, breach of the standard of care under ORS 677.095(1), causation, and damages. Most claims demand expert testimony to establish whether you met the standard of care ordinarily expected of physicians in similar circumstances in your community.
What Your Policy Covers
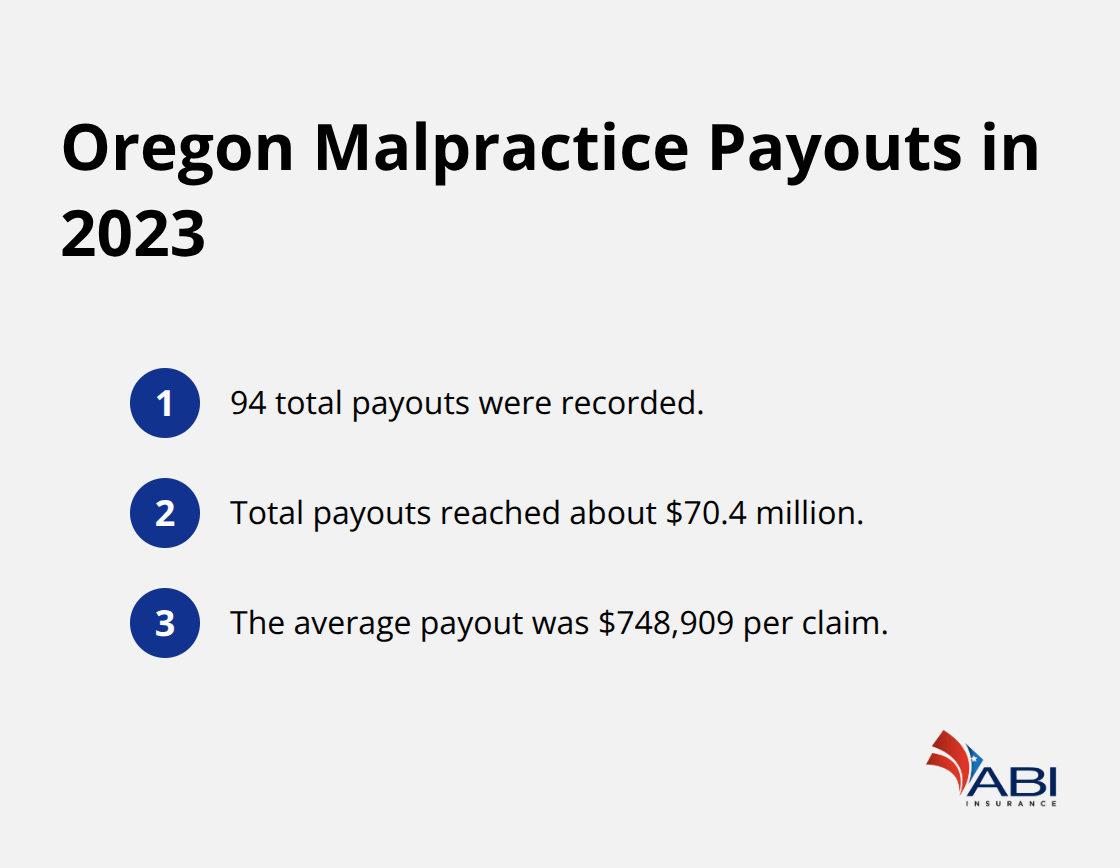
Your policy covers both economic damages (added medical costs, lost wages, household services) and noneconomic damages (pain and suffering, emotional distress, loss of quality of life). In 2023, Oregon saw 94 malpractice payouts totaling about $70.4 million, with an average payout of $748,909 according to the National Practitioner Data Bank. The policy also covers defense costs for administrative actions by Medicare, Medicaid, your state medical board, credentialing reviews, and the DEA, though you must verify this protection is included in your specific policy.
Critical Exclusions You Must Know
Standard policies do not cover intentional misconduct, criminal acts, or violations of federal fraud laws. Most carriers exclude coverage for gross negligence or recklessness, and they do not protect you against claims arising from unlicensed practice or practicing outside your scope. Policies also typically exclude coverage for sexual misconduct, substance abuse, or violations of professional ethics unrelated to patient care decisions.
How Defense Costs Affect Your Real Protection
Defense costs may be inside or outside your policy limits depending on how the policy is structured; this distinction dramatically affects your actual protection. A $1 million per-claim limit with defense costs inside that limit means your available coverage shrinks as legal fees accumulate. A policy with defense costs outside the limit preserves the full $1 million for damages. You must review sample policy language before purchasing to confirm whether defense costs count toward your limits.
Reporting Requirements and Deadlines
Most policies require you to report claims or potential claims promptly; failure to report within the deadline specified in your policy can result in denial of coverage. Oregon’s two-year statute of limitations from discovery and five-year ultimate repose from treatment create fixed deadlines for filing. Understanding your policy’s reporting window matters because these legal deadlines move fast, and your insurer needs time to mount an effective defense. The next section examines how to assess your specific risk exposure and select limits that match your practice.
Why Oregon Clinicians Need Medical Liability Coverage
Credentialing Requirements Override the Lack of Legal Mandate
Oregon does not legally mandate physicians to carry medical malpractice insurance, but this absence of a mandate creates a false sense of security. Most hospitals, surgical centers, and clinic networks require minimum coverage as a condition of credentialing and staff privileges, typically $1 million per claim and $3 million aggregate, though many facilities demand higher limits. Before you accept any position, verify these requirements in writing because credentialing standards vary widely by institution and specialty. Failure to carry the required coverage blocks your access to patient care settings where you generate revenue, effectively ending your ability to practice.
Board Investigations and Administrative Defense Costs
The Oregon Medical Board does not mandate coverage either, but it investigates complaints and can initiate disciplinary action independent of malpractice claims. When a patient files a complaint with the board, your insurer typically handles the defense, though you should confirm your policy covers administrative board actions, Medicare and Medicaid investigations, DEA inquiries, and credentialing reviews. Many standard policies include this regulatory or administrative coverage, but you must verify it exists before a problem arises because gaps in this protection leave you defending yourself out-of-pocket against state investigators.
The Financial Reality of Uninsured Claims
Oregon saw 94 malpractice payouts in 2023 totaling approximately $70.4 million according to the National Practitioner Data Bank, with an average payout of $748,909 per claim. A single obstetrics claim can generate $150,000 or more in defense costs alone before trial, and damages in complex cases routinely exceed $1 million.
Without coverage, a single claim wipes out most practitioners’ personal assets and retirement savings. Beyond the direct financial hit, uninsured claims damage your reputation, trigger board investigations, and make future credentialing nearly impossible.
Risk Management Resources and Prevention Programs
Your policy provides risk management resources, CME opportunities, and patient safety tools that reduce the likelihood of claims. Carriers like The Doctors Company, which operates as a doctor-owned mutual with $12 billion in assets and about 175,000 members, invest heavily in these prevention programs because they reduce the frequency and severity of claims across their membership. These resources are not available to uninsured practitioners. Oregon’s two-year statute of limitations from discovery and five-year ultimate repose from treatment mean claims can surface years after the incident occurred, so coverage protects you throughout your career and into retirement.
Occurrence Versus Claims-Made: Long-Term Cost Implications
Occurrence policies cover incidents during the policy period, regardless of when the claim is filed, eliminating the need for expensive tail coverage at retirement or during practice transitions. Claims-made policies cost less upfront but saddle you with tail coverage expenses of 40 to 150% of your final-year premium when you leave practice, potentially a $110,000 bill for a $55,000 annual premium in obstetrics. The choice between these policy types shapes your total lifetime cost and your financial obligations when you transition out of practice. Understanding this distinction now prevents costly surprises later.
How to Match Coverage to Your Practice Reality
Map Your Facility Requirements First
Start by identifying every clinical setting where you work and the minimum coverage each facility demands. A hospital might require malpractice coverage limits for hospital credentialing, while an urgent care center accepts $500,000 per claim, and a surgical center demands $2 million per claim and $5 million aggregate. One policy rarely satisfies all these requirements. You need to identify the highest threshold across all facilities where you hold clinical privileges, use that as your MPL limit, and build your coverage to that level. Contact credentialing at each facility in writing and document their exact limits before you purchase.
Understand How Your Specialty Affects Your Cost
High-risk specialties like obstetrics and orthopedic surgery pay substantially more than primary care. An OB/GYN with major surgery procedures faces undiscounted rates around $39,881 annually for $1 million per claim and $3 million aggregate coverage according to state-filed data, while family medicine without surgery runs approximately $7,684 for the same limits. Your specialty determines your baseline cost, but your claims history, county, and prior experience shape your final premium. If you have previous claims on your record, expect to pay significantly more or face coverage restrictions from some carriers.
Evaluate Defense Costs and Policy Structure
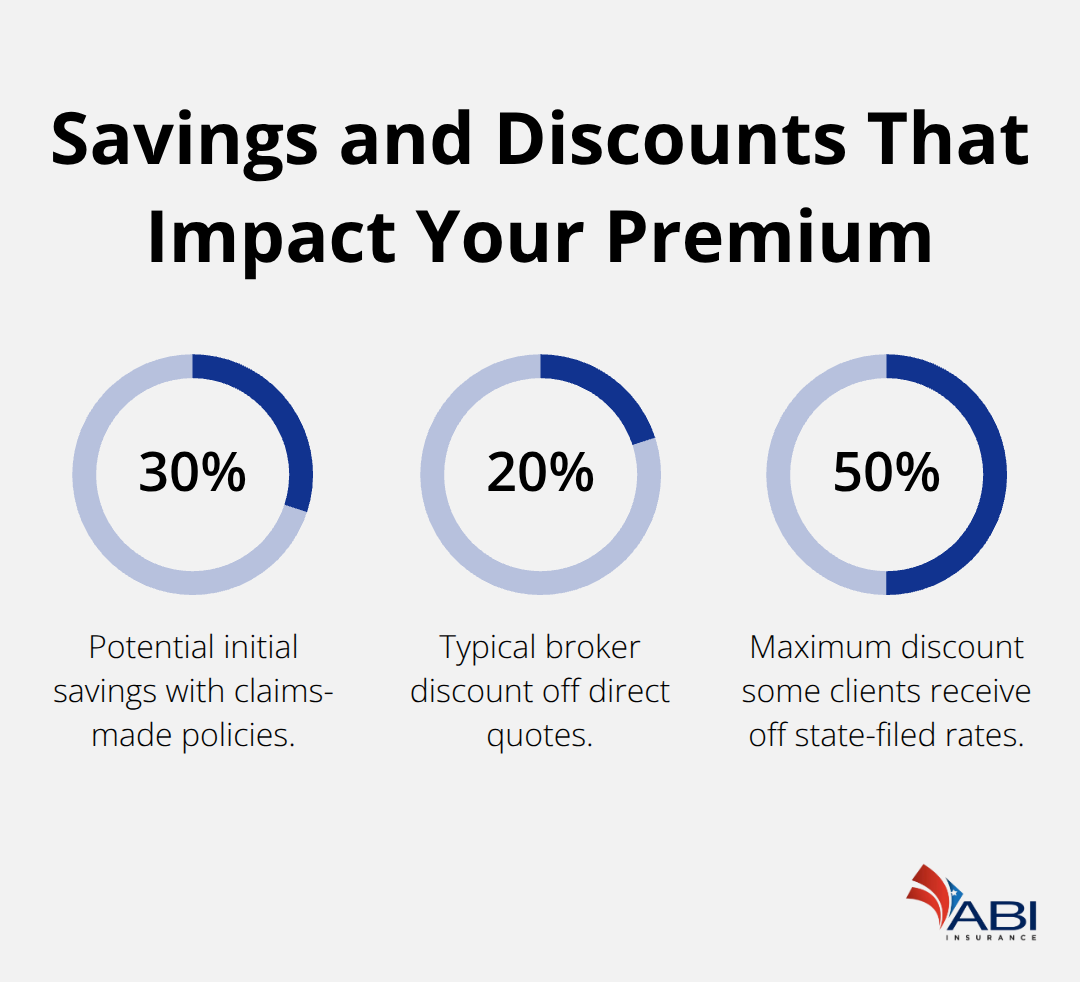
Defense costs matter far more than most practitioners realize, and this single factor can collapse your protection when you need it most. Obstetrics claims routinely generate $150,000 or more in legal fees before trial, and if your policy counts defense costs inside your $1 million limit, you have only $850,000 or less left for actual damages when the bill arrives. Review sample policy language from any carrier before you commit and explicitly confirm whether defense costs sit inside or outside your per-claim limit. Occurrence policies eliminate tail coverage obligations because they cover incidents during the policy period regardless of when claims are filed, making them superior for practitioners planning long-term careers or eventual retirement, though they cost more upfront. Claims-made policies cost 20 to 30% less initially but demand tail coverage when you leave practice, and that tail bill runs 40 to 150% of your final-year premium (a $55,000 obstetrics premium produces roughly $22,000 to $33,000 in tail costs, though some policies charge closer to 200 of final premium in high-risk fields). Do not underestimate this obligation. Negotiate tail coverage responsibility into your employment contract now, because employers sometimes cover tail for departing physicians and sometimes do not, and the difference between a covered tail and a self-paid tail reaches $110,000 in expensive specialties.
Optimize Deductibles and Shop Strategically
Increasing your deductible will lower your premium. Run the math on whether that savings justifies the higher out-of-pocket exposure if a claim hits. Shop annually with a broker who represents multiple carriers because brokers access better discounts and negotiate site-specific terms. Verify the carrier’s financial strength through AM Best or Fitch ratings, and confirm they hold an A rating or better; weaker carriers can fail during adverse claim years, leaving you unprotected when claims actually arrive. The Doctors Company operates as a doctor-owned mutual with $12 billion in assets and approximately 175,000 members, providing the stability and nationwide expertise that independent practitioners need.
Verify Administrative Coverage and Long-Term Protection
Confirm your policy includes coverage for Medicare and Medicaid investigations, state medical board actions, credentialing reviews, and DEA matters, because gaps in administrative defense coverage force you to hire your own attorney when the board investigates. Oregon’s two-year statute of limitations from discovery and five-year ultimate repose from treatment mean claims surface years later, so your coverage must protect you throughout your career and extend into retirement if you choose occurrence policies or secure tail coverage if you select claims-made.
Final Thoughts
Clinician medical liability coverage is not optional in Oregon, regardless of what state law says. Your hospitals, surgical centers, and clinic networks will demand it before you see your first patient, and a single uninsured claim destroys your financial security and career trajectory. The 94 malpractice payouts in Oregon in 2023 totaling $70.4 million prove this is not a theoretical risk. It happens to real practitioners every year, with average payouts exceeding $748,000.
Document the exact coverage requirements from every facility where you work, identify your specialty’s baseline premium range, and decide whether an occurrence or claims-made policy fits your long-term career plans. If you choose claims-made coverage, negotiate tail coverage responsibility into your employment contract now rather than facing a $110,000 surprise bill when you leave practice. Shop with a broker who represents multiple carriers; brokers access discounts up to 50% off state-filed rates and can negotiate site-specific terms that direct shopping cannot match.
Professional guidance matters more than you might think. At ABI Insurance, our team has spent more than 40 years helping medical professionals across the Portland metro area and beyond secure the right clinician medical liability coverage for their practices. Contact us to discuss your coverage needs and receive a personalized quote tailored to your practice.


 Understanding Claims-Made Medical Malpractice Insurance: A Complete Guide









