
One wrong decision about commercial auto liability limits can cost your small fleet thousands in uninsured losses. Most fleet owners either carry too little coverage and face personal liability or overpay for limits they don’t need.
At ABI Insurance, we’ve seen firsthand how the right coverage protects your business when accidents happen. This guide walks you through state requirements, industry standards, and how to calculate the exact limits your fleet needs.
What Commercial Auto Liability Actually Covers
Commercial auto liability protects your business when a driver causes injury or property damage to someone else while driving a company vehicle. This coverage pays for medical bills, lost wages, pain and suffering, and repair costs up to your policy limit. If a driver hits another car and the other driver’s medical expenses total $75,000, liability coverage pays that claim. Without it, you pay out of pocket and face potential lawsuits against your business.
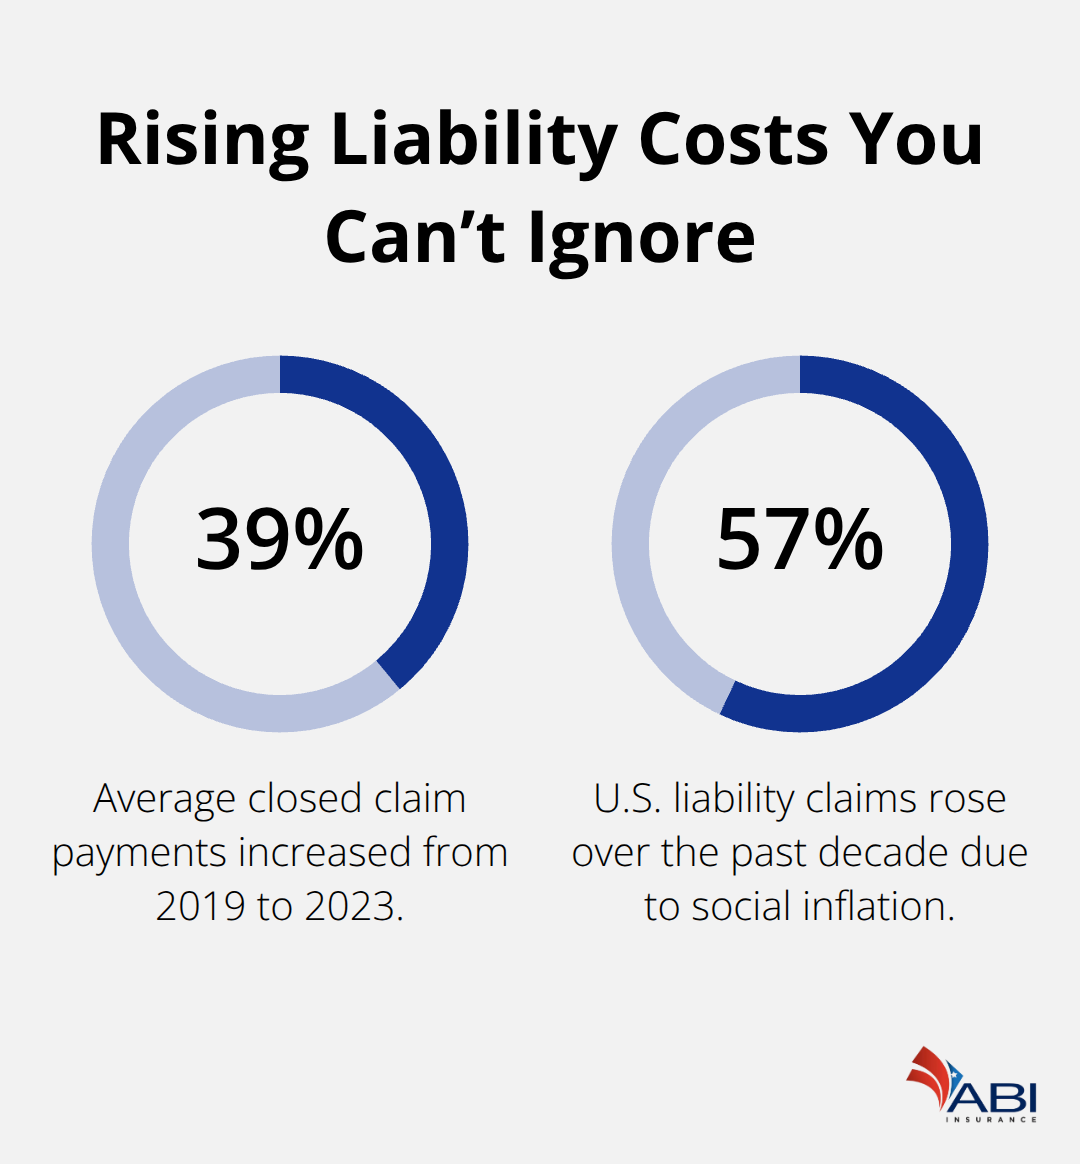
The Dominion Risk analysis shows that average closed claim payments rose 39% between 2019 and 2023, meaning incidents that cost $50,000 five years ago now cost roughly $70,000. Your personal assets become vulnerable if a claim exceeds your coverage limit.
The Personal Auto Insurance Trap
Many small fleet owners mistakenly believe their personal auto insurance covers business driving, but it does not. Most personal policies exclude regular business use, and insurers will deny claims if they discover work-related driving. This gap exposes you to catastrophic financial risk and leaves accident victims with no compensation source except your personal assets.
The Real Cost of Underinsuring Your Fleet
Most small fleets carry minimum state-required limits, which is a dangerous strategy. State minimums typically range from $15,000 to $50,000 per accident depending on your location, but these amounts cover almost nothing in today’s liability environment. A single serious injury claim easily reaches $250,000 to $500,000.
The Insurance Information Institute reports that liability claims in the U.S. rose 57% over the past decade due to social inflation. Court awards and settlement demands keep climbing as juries award larger damages for pain and suffering. A fleet with $25,000 in liability coverage facing a $150,000 claim becomes responsible for the $125,000 gap.
You cannot declare bankruptcy to escape commercial auto liability judgments, so creditors pursue your business assets, equipment, and future revenue for years. The practical solution is carrying 5 to 10 times your state minimum, which costs far less than the financial exposure you accept by underinsuring.
Why Your Fleet Size and Vehicle Type Matter
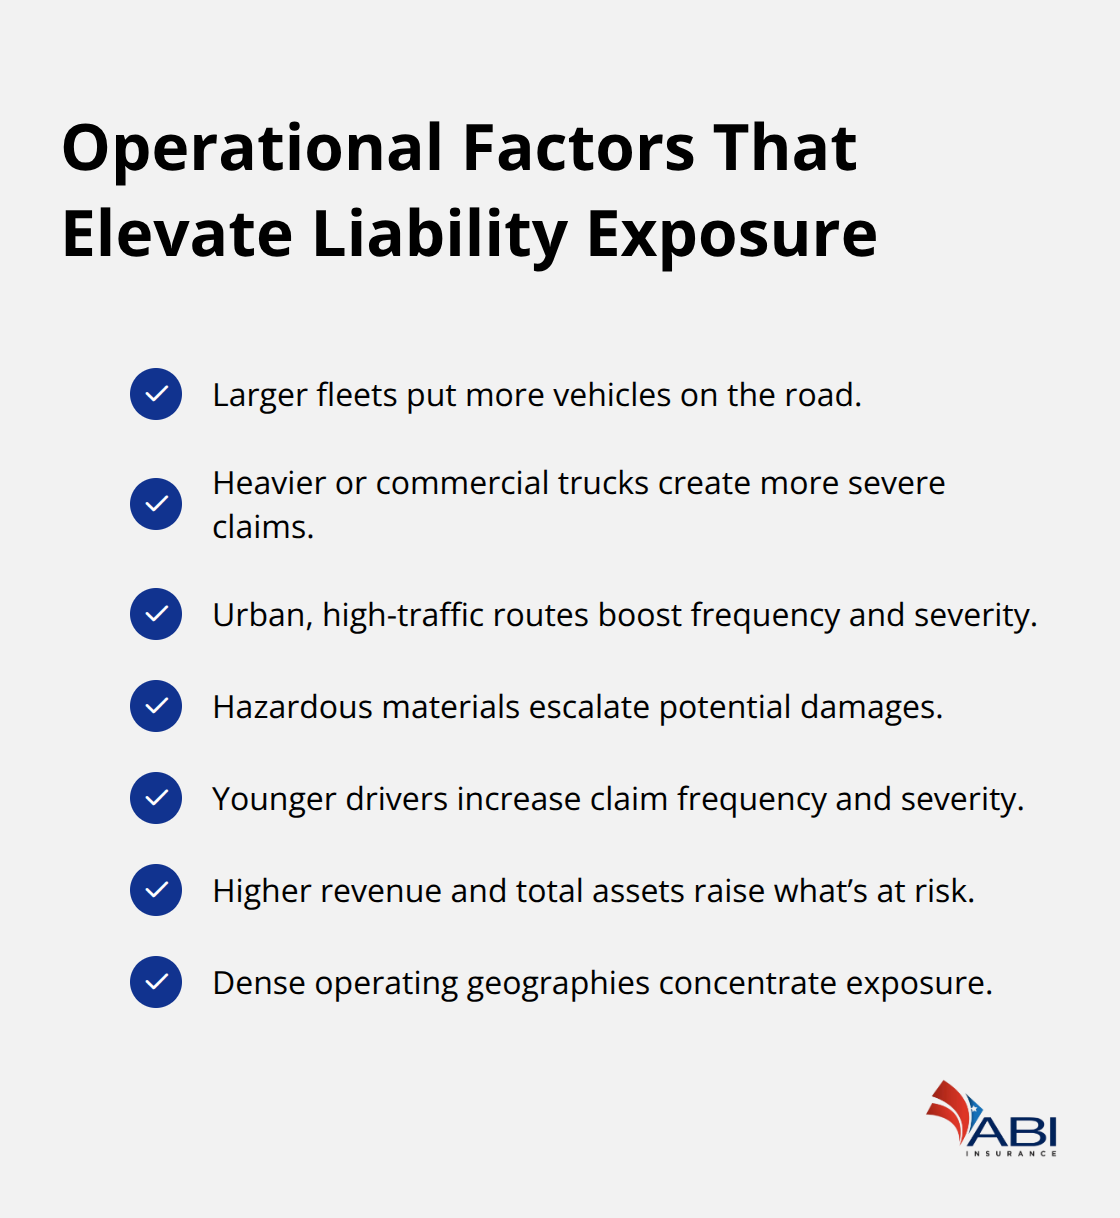
A plumber with one cargo van faces different risks than a delivery service running five vehicles through downtown traffic. Vehicle type, driver experience, and operational patterns determine how much liability exposure you actually have. Vehicles transporting hazardous materials or operating in high-traffic urban areas generate higher claims frequency and severity.
A single accident involving a delivery truck in a congested area can injure multiple people and damage multiple vehicles, pushing claims into the $500,000+ range. Your fleet’s assets and annual revenue also factor into appropriate coverage levels. A business with $2 million in equipment and $500,000 annual revenue needs enough liability coverage to protect both.
If a claim exhausts your liability limit and judgment creditors seize your business assets and future earnings, you’ve failed to transfer risk to the insurance company. This is why working with an insurance professional to assess your specific operational risk matters for small fleets. he next section walks you through how state requirements and industry standards shape your coverage decisions.
State Minimum Requirements and Industry Standards
Every state except Virginia and New Hampshire mandates commercial auto liability insurance, but the minimum amounts fall far short of protecting your business. Most states set minimums between $15,000 and $50,000 per accident — amounts that vanish instantly when a serious injury occurs. A single collision involving multiple vehicles and injured parties generates medical costs, lost wages, and pain-and-suffering damages that easily exceed $200,000. Your state’s minimum represents the legal floor, not a sound business strategy. Carrying only state minimums exposes your fleet to catastrophic financial risk that no prudent operator should accept.
The Dangerous Gap Between Legal Minimums and Real Claims
Insurance carriers and risk management professionals recommend liability limits five to ten times higher than state minimums for small fleets. Nationwide suggests at least $100,000 per vehicle as a baseline, with recommended ranges climbing to $500,000 or $1,000,000 depending on your operation. This recommendation reflects actual claim data and the trajectory of damage awards over time. The Insurance Information Institute documented that liability claims rose, driven by social inflation, meaning juries award substantially more for pain and suffering than they did previously. Courts increasingly view businesses as deep pockets capable of paying larger judgments, so your coverage limit directly affects your financial exposure when accidents happen.
How Fleet Operations Shape Your Coverage Needs
Fleet size, vehicle type, and operational geography create different risk profiles that require different coverage levels. A plumber running one service van through suburban neighborhoods faces materially lower exposure than a delivery service operating five vehicles through downtown congestion during rush hours. Vehicles carrying hazardous materials, operating in high-density urban areas, or driven by younger operators, generate higher claim frequency and severity. Your annual revenue and total business assets also matter significantly.
If a judgment creditor seizes your equipment, inventory, and future earnings, you’ve failed to adequately transfer risk through insurance. A business generating $750,000 annual revenue with $300,000 in equipment needs enough liability coverage to protect both.
Finding Your Coverage Sweet Spot
How Much Liability Coverage Does Your Fleet Actually Need
Calculate Your Total Financial Exposure
Start with your total business assets and annual revenue, then work backward to determine adequate liability coverage. A fleet operating with $400,000 in vehicles and equipment and $600,000 in annual revenue faces genuine exposure that state minimums cannot address. A single serious injury claim reaches $250,000 to $500,000 in today’s environment, which means your coverage limit must exceed your total financial stake in the business. Add equipment value, vehicle inventory, accounts receivable, and one year of operating profit to calculate your potential loss.
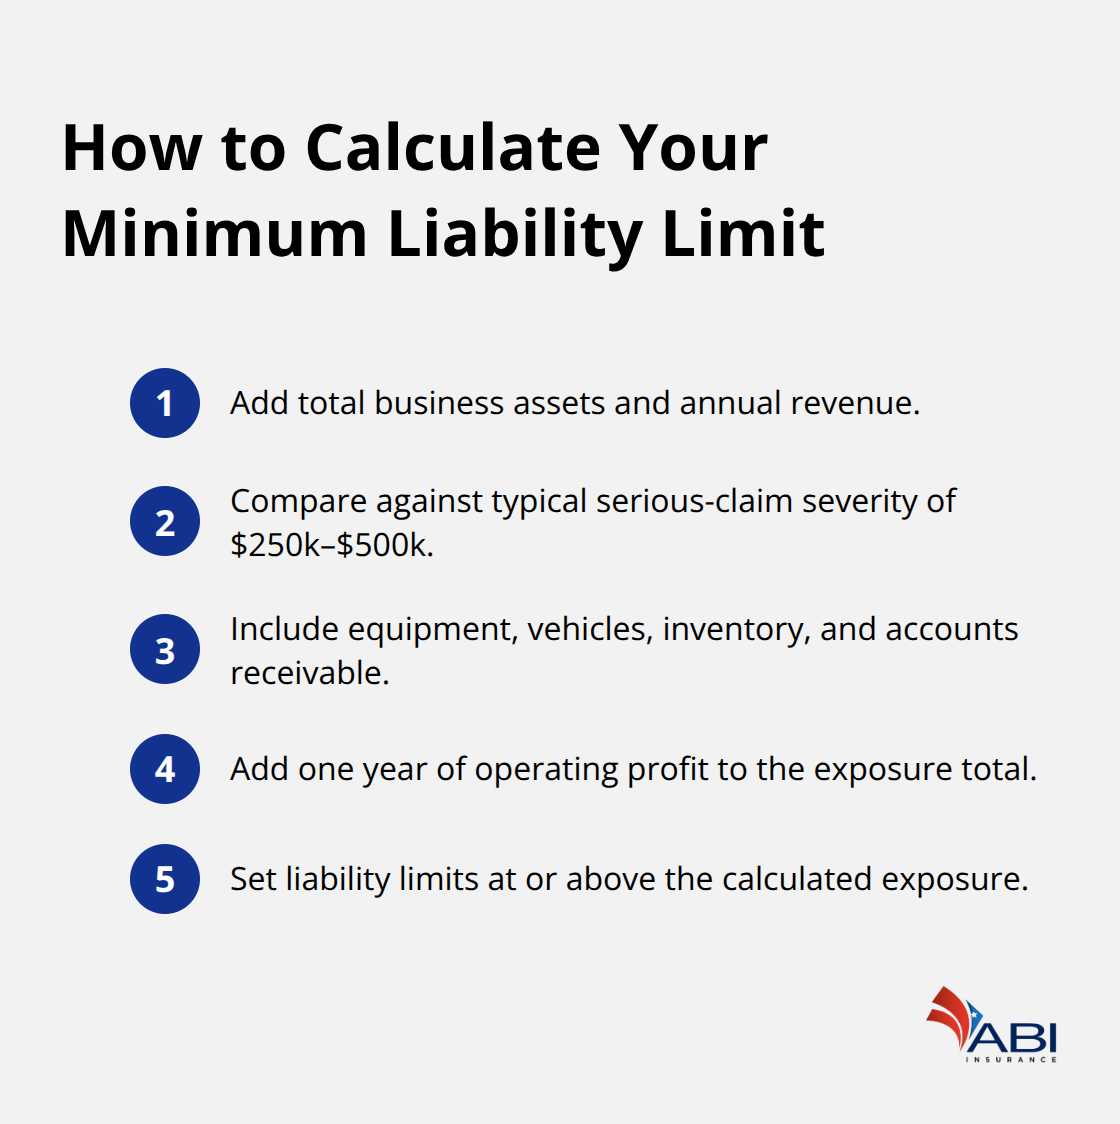
This number tells you the minimum liability limit needed to protect your business from judgment creditors. Most small fleet owners discover they need $1,000,000 in coverage once they account for their actual financial exposure rather than accepting industry averages or state minimums.
Assess Your Operational Risk Profile
Your operational risk profile determines whether you sit at the lower or upper end of that range. A service business with one vehicle, minimal traffic exposure, and an experienced driver requires less coverage than a delivery operation running five vehicles through congested urban streets with younger operators. Driver age matters substantially. Operators under 25 generate significantly higher claim frequency and severity, which means fleets with younger drivers should carry higher limits. Vehicle type also shapes your exposure: commercial trucks operating in dense traffic create more claim potential than service vans making residential calls.
Geographic location influences risk as well. fleet operating primarily in rural areas faces lower exposure than one concentrated in downtown Portland or Seattle. Review your motor vehicle records for all drivers and identify any violations or past accidents. Factor that history into your coverage calculation. An insurance professional can assess these specific operational factors and recommend appropriate limits rather than forcing you to guess based on generic benchmarks.
Match Coverage to Your Specific Operation
Your coverage decision should reflect your specific operation, not theoretical industry standards or what other fleets in different circumstances carry. A delivery service with five vehicles in high-traffic areas needs substantially more protection than a plumbing contractor with one service van. Driver composition, vehicle types, and geographic concentration all shift your appropriate coverage level. Insurance professionals evaluate these factors systematically and recommend limits that protect your assets without overpaying for excess capacity.
Revisit your coverage decision annually as your fleet grows, driver composition changes, or your business expands into new geographic areas or service lines. Each operational shift alters your exposure profile and may warrant higher limits to match your increased financial stake in the business.
Final Thoughts
Selecting appropriate commercial auto liability limits requires honest assessment of your fleet’s financial exposure and operational risk, not guessing based on state minimums or what competitors carry. Your coverage decision directly determines whether a serious accident depletes your business assets or transfers that risk to your insurance company. Most small fleet owners need $500,000 to $1,000,000 per vehicle in liability limits once the total business value is calculated and today’s elevated claim costs are accounted for.
Start your coverage review by documenting your total fleet value, annual revenue, and driver composition, then compare that financial stake against your current commercial auto liability limits. If your current limits fall below your total business value, you accept personal liability for the difference. An insurance professional can assess your specific operational factors — vehicle types, driver age, geographic concentration, and traffic exposure — and recommend limits that match your actual risk profile.
Review your commercial auto liability limits annually as your fleet grows or your business expands into new service areas. Each new vehicle, additional driver, or geographic shift changes your exposure profile and may warrant higher limits. Contact us to review your current limits and ensure your fleet carries adequate protection against today’s rising claim costs.


 Clinician Medical Liability Coverage: A Practical Guide for Oregon Practitioners









