
A single lawsuit or accident can wipe out years of financial progress. Most homeowners and auto policies cap liability coverage at $300,000 to $500,000, far below what you might owe if someone is seriously injured on your property or in an accident you cause.
Personal umbrella insurance benefits extend well beyond these limits, protecting your assets when standard policies fall short. At ABI Insurance, we’ve seen how this extra layer of coverage prevents financial devastation for families and business owners alike.
What Your Umbrella Policy Covers
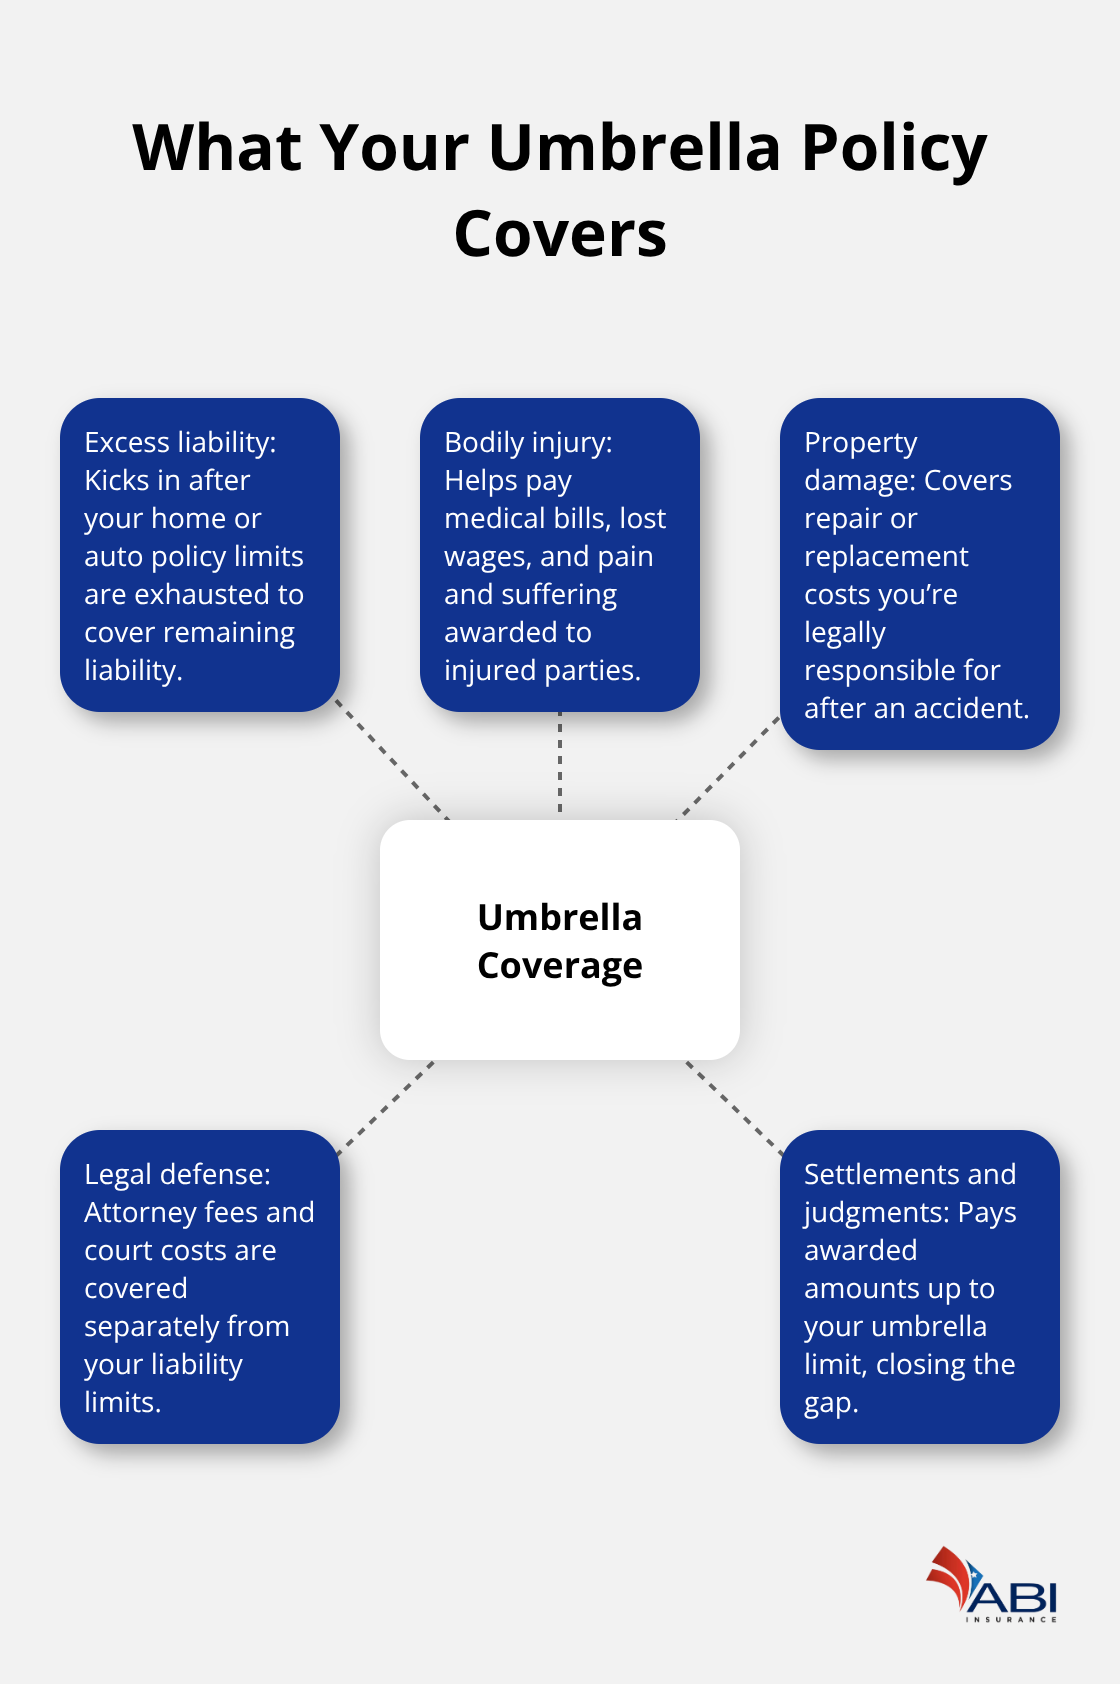
Personal umbrella insurance activates when your home or auto liability limits are exhausted. If someone sues you for $1 million after a serious accident and your auto policy maxes out at $500,000, your umbrella policy covers the remaining $500,000 in judgment costs. This protection applies to bodily injury claims — medical bills, lost wages, pain and suffering — and property damage claims alike. Umbrella policies typically start at $1 million in coverage and cost between $300 and $500 annually, making them one of the most affordable ways to protect substantial assets.
When Liability Claims Reach Beyond Standard Limits
Your homeowners policy covers someone injured on your property, but only up to its stated limit. Your auto policy covers accidents you cause, again with a cap. A serious injury claim can easily exceed $500,000 when you factor in medical treatment, rehabilitation, and lost income. An umbrella policy fills this gap. It covers defense attorneys, court costs, settlements, and final judgments — expenses that mount quickly in complex liability cases.
Legal Defense Becomes Your Responsibility
Your homeowners and auto policies include some legal defense coverage, but their attorneys work within strict policy limits. Once your policy limit is reached, the insurance company stops paying for defense costs, leaving you to hire your own counsel. Personal umbrella insurance covers legal defense costs separately from your coverage limits, meaning you don’t eat into your $1 million protection while fighting a lawsuit. This distinction matters enormously in cases that drag through appeals or involve multiple defendants. Umbrella coverage protects both your assets and your ability to mount a proper legal defense.
What Happens When Standard Policies Fall Short
Most homeowners and auto policies cap liability coverage at $300,000 to $500,000, far below what you might owe if someone is seriously injured on your property or in an accident you cause. A single lawsuit or accident can wipe out years of financial progress. Umbrella insurance helps cover the gap between your standard policy limits and the actual judgment amount. Families and business owners across the Portland metro area face this risk every day, which is why understanding your coverage gaps matters before a claim arrives.
Who Needs Personal Umbrella Insurance
Assets Create Liability Exposure
Personal umbrella insurance isn’t reserved for the wealthy, though high-net-worth individuals certainly benefit from it. Anyone with meaningful assets — a house, savings, investments, or a business — faces real financial exposure that standard policies leave uncovered. A $2 million judgment against you doesn’t care whether you own a modest home or a mansion. The damage to your financial future hits equally hard. Families across the Portland metro area earning $75,000 to $150,000 annually carry umbrella policies because they understand the gap between their $300,000 homeowners limit and what a serious injury claim could cost. These aren’t wealthy people protecting inherited fortunes; they’re ordinary people protecting years of disciplined saving.
Homeowners Face Specific Liability Risks
Parents who are homeowners face particular liability exposure that most underestimate. A teenager’s friend suffers a spinal injury at your pool. Your dog bites a neighbor. A guest slips on your icy driveway. These scenarios happen frequently, and medical costs escalate rapidly.
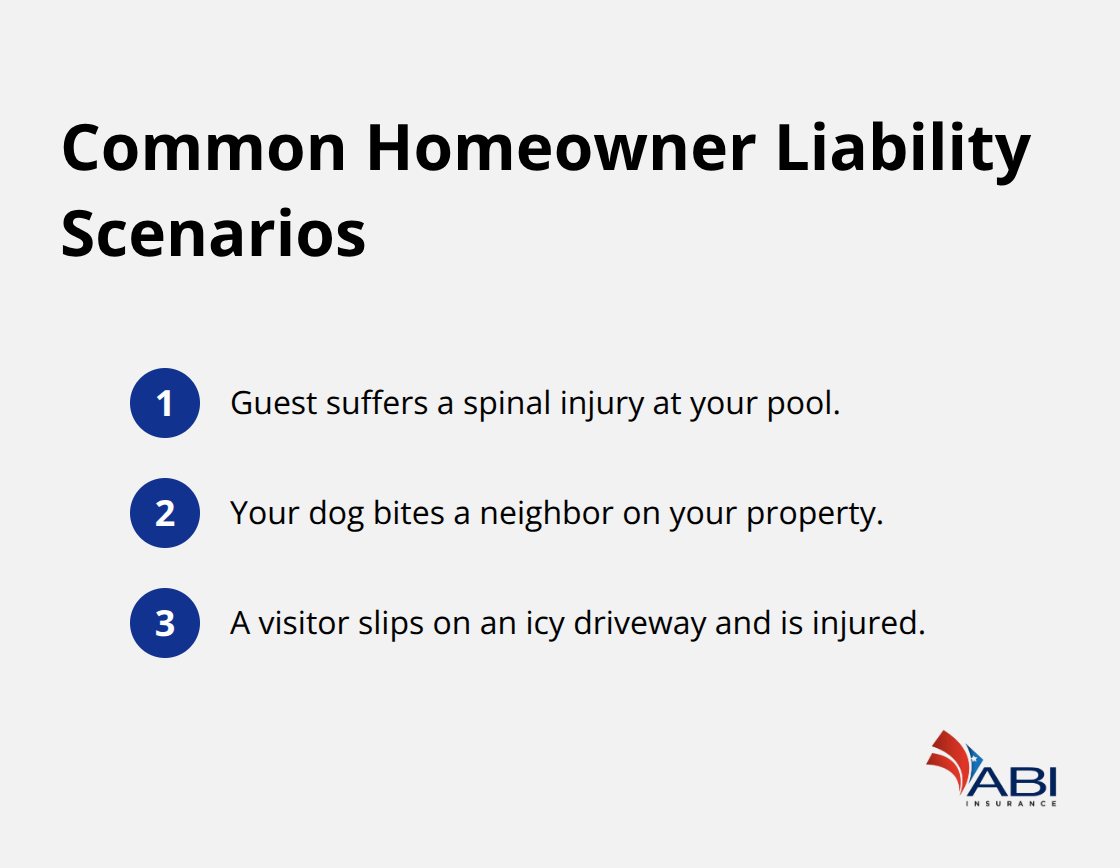
Your homeowners policy covers the incident, but only to its stated limit. After that, the remaining judgment comes directly from your bank account, retirement savings, or future wages.
Self-Employed Professionals Need Extra Protection
Business owners and self-employed professionals face even sharper exposure because they often lack the corporate liability shield that protects employees of larger companies. A contractor causes property damage during a job. A consultant faces a lawsuit for professional negligence. A salon owner confronts a customer injury claim. These situations create judgments that easily surpass standard commercial policy limits. Self-employed professionals in the Portland area have lost home equity and retirement accounts because their business liability coverage maxed out at $500,000 while the actual judgment reached $1.2 million.
Affordable Protection Against Financial Devastation
Umbrella insurance costs about $300 to $500 annually for $1 million in coverage, making it extraordinarily inexpensive protection against scenarios that destroy financial security. This price point means that calculating your coverage needs becomes the real challenge — determining how much protection matches your assets and lifestyle.
How Much Umbrella Coverage Do You Need
Calculate Your Total Assets
List your total assets — home value, savings accounts, investment portfolios, vehicles, retirement accounts, and any business interests. This number determines your financial exposure in a lawsuit. If you own a $400,000 home, carry $150,000 in savings, and have $200,000 in retirement accounts, your total assets reach $750,000. A $1 million judgment against you wipes out everything and leaves creditors pursuing your wages for years.
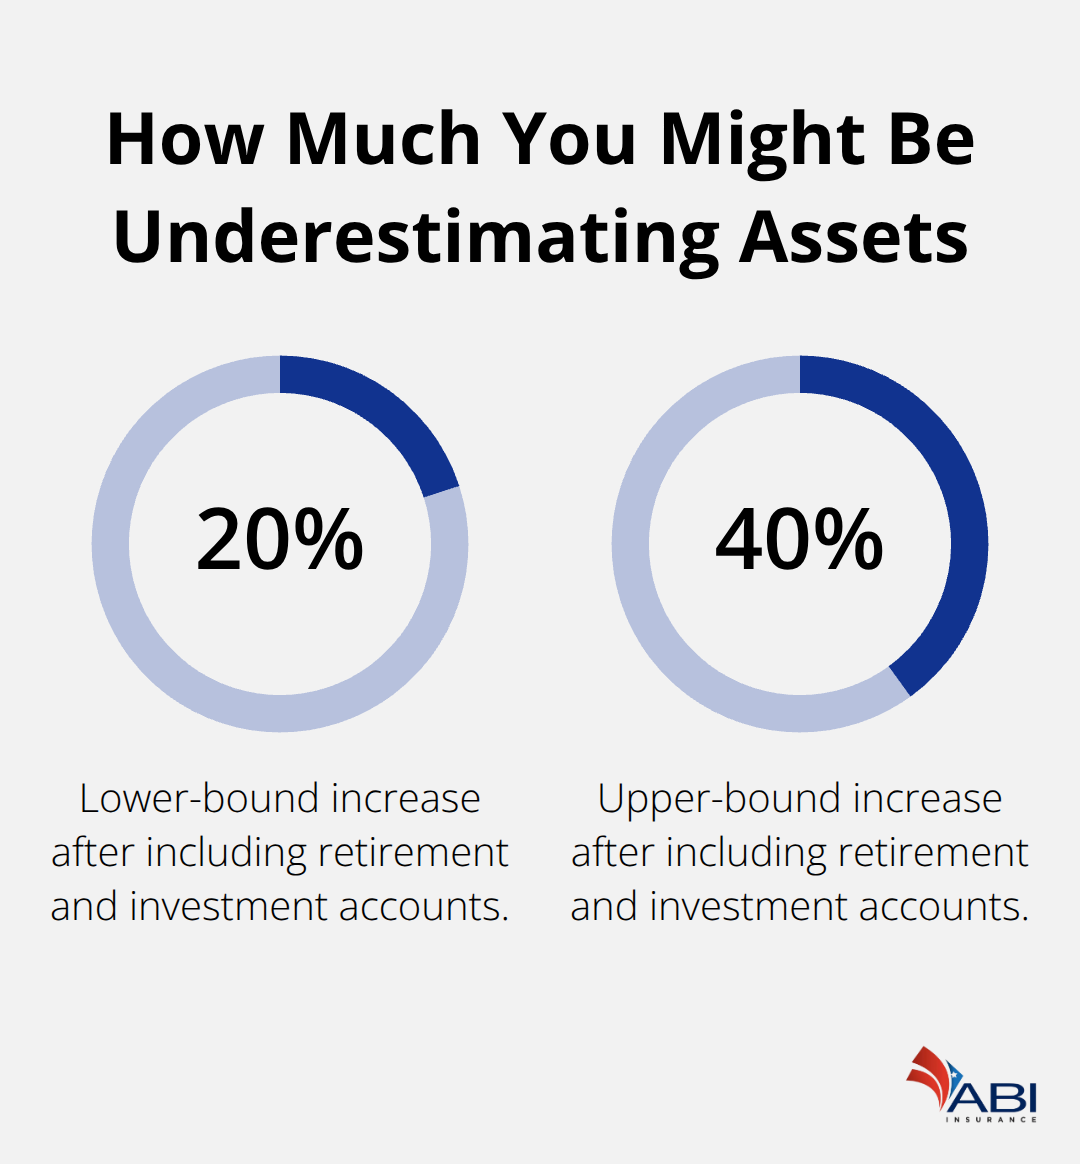
Umbrella coverage should match your total net worth. Most homeowners underestimate what they own when they sit down and calculate it. Your assets exceed what you thought by 20 to 40 percent once you account for all retirement savings and investment accounts.
Assess Your Lifestyle and Activities
Your lifestyle and activities matter to your asset base. A homeowner with a swimming pool faces higher liability exposure than someone without one. Parents who host frequent gatherings invite more risk than those who don’t. Self-employed contractors working on client properties face different exposure than office-based professionals.
Someone who drives frequently for rideshare or business purposes carries greater accident risk than someone who drives only locally for personal errands. These lifestyle factors don’t change your asset base, but they do change how likely you are to face a claim that exhausts your standard policy limits.
Review Your Current Policy Limits
Review your current homeowners and auto policy limits with your agent — not online, but in a conversation where you discuss specific scenarios. If your homeowners policy caps liability at $300,000 and you own $750,000 in assets, a $600,000 judgment leaves you personally liable for $300,000. A $1 million umbrella policy costs roughly $300 to $500 annually and covers that gap entirely.
Match Coverage to Serious Injury Claims
This data suggests that most homeowners with meaningful assets need at least $1 million in umbrella coverage, with many benefiting from $2 million coverage.
Higher coverage amounts cost less per million dollars of protection, so a $2 million umbrella policy often costs only about $600 to $700 annually — a negligible expense compared to the financial devastation it prevents. Your agent can model different coverage levels against your specific assets and activities to show you exactly where the protection gaps exist.
Final Thoughts
Personal umbrella insurance protects your assets when a serious liability claim arrives, and your standard homeowners or auto policy maxes out within weeks. A $1 million judgment against you doesn’t wait for you to consider coverage gaps — it comes through a lawsuit, and that’s when umbrella coverage prevents the financial devastation that wipes out years of savings and forces wage garnishment for years afterward. The protection is absolute, covering the judgment amount, legal defense costs, and court expenses that would otherwise come directly from your bank account.
Review your current homeowners and auto policy limits with an insurance professional who understands your specific assets and lifestyle rather than estimating these numbers alone. A conversation with an agent reveals coverage gaps you would miss on your own and shows you exactly where your $300,000 or $500,000 policy limits fall short against your total net worth. They’ll model different umbrella coverage amounts to show you the actual cost difference between $1 million and $2 million in protection, with most policies costing between $300 and $500 annually for $1 million in coverage.
Contact ABI Insurance to review your current coverage and determine the right umbrella protection for your situation. We’ve guided families and business owners across the Portland metro area through this exact process, helping you match your umbrella coverage to your real financial exposure. Peace of mind comes from knowing that if a serious accident happens, your assets and future earnings remain protected.


 Medical Professional Liability Solutions: How Oregon Clinicians Can Protect Their Practice









