
Your wealth creates exposure that standard insurance simply doesn’t cover. A lawsuit or accident involving your properties, vehicles, or assets could threaten everything you’ve built.
High net worth umbrella insurance in Portland fills those gaps with additional liability protection beyond what homeowners and auto policies provide. We at ABI Insurance help high net worth families understand exactly how much coverage they need and why it matters.
Why High Net Worth Individuals Need Umbrella Insurance
Standard homeowners and auto policies in Oregon carry liability limits that fall dangerously short of what high net worth households actually need. Oregon’s minimum auto liability requirements are $25,000 per person for bodily injury and $20,000 for property damage, while typical homeowners policies start liability at $300,000. A single lawsuit from a serious accident on your property or involving one of your vehicles can easily exceed these limits and put your personal assets at risk.
If a guest suffers a major injury at your home, a jury could award damages far beyond what your standard policy covers, leaving you personally liable for hundreds of thousands of dollars. Umbrella insurance fills this gap with additional liability coverage that starts where your underlying policies end, protecting your net worth from catastrophic claims.
Multiple Properties Multiply Your Exposure
Wealthy Portland residents often own vacation homes, rental properties, or investment real estate beyond their primary residence. Each property you own represents a separate source of liability exposure. If a tenant is injured in your rental property and the landlord’s insurance limit is insufficient, umbrella coverage protects you from the difference between what the policy pays and what a court awards. Boat ownership, luxury vehicles, and other high-value assets increase your liability risk significantly. Umbrella insurance adds personal liability protection on top of your auto, homeowners, and watercraft policies. Without umbrella protection, a single incident at any of your properties could force you to liquidate investments or sell assets to cover a judgment.
Defense Costs Create Hidden Financial Threats
Most people focus on the damages a lawsuit might award, but the legal costs to defend yourself are equally damaging. Umbrella insurance covers your defense costs, including attorney fees, expert witness testimony, and court expenses, which can reach $50,000 or more in complex cases. These costs apply whether you ultimately win or lose the case. A high net worth individual facing a serious liability claim needs experienced legal representation, and that representation is expensive. Your umbrella policy pays these bills directly, preventing them from draining your liquid assets while your case proceeds. Understanding what your current policies cover and what they leave exposed is the first step toward comprehensive asset protection.
Coverage Gaps in Standard Policies for Wealthy Households
Homeowners Liability Falls Short of Your Net Worth
Your homeowners policy for personal liability is probably about $300,000. This number sounds substantial until you face a real lawsuit. A jury verdict for permanent disability, chronic pain, or loss of income reaches $2 million, $5 million, or higher depending on the severity of the injury and the defendant’s perceived wealth. Courts know you have assets, and juries award accordingly.
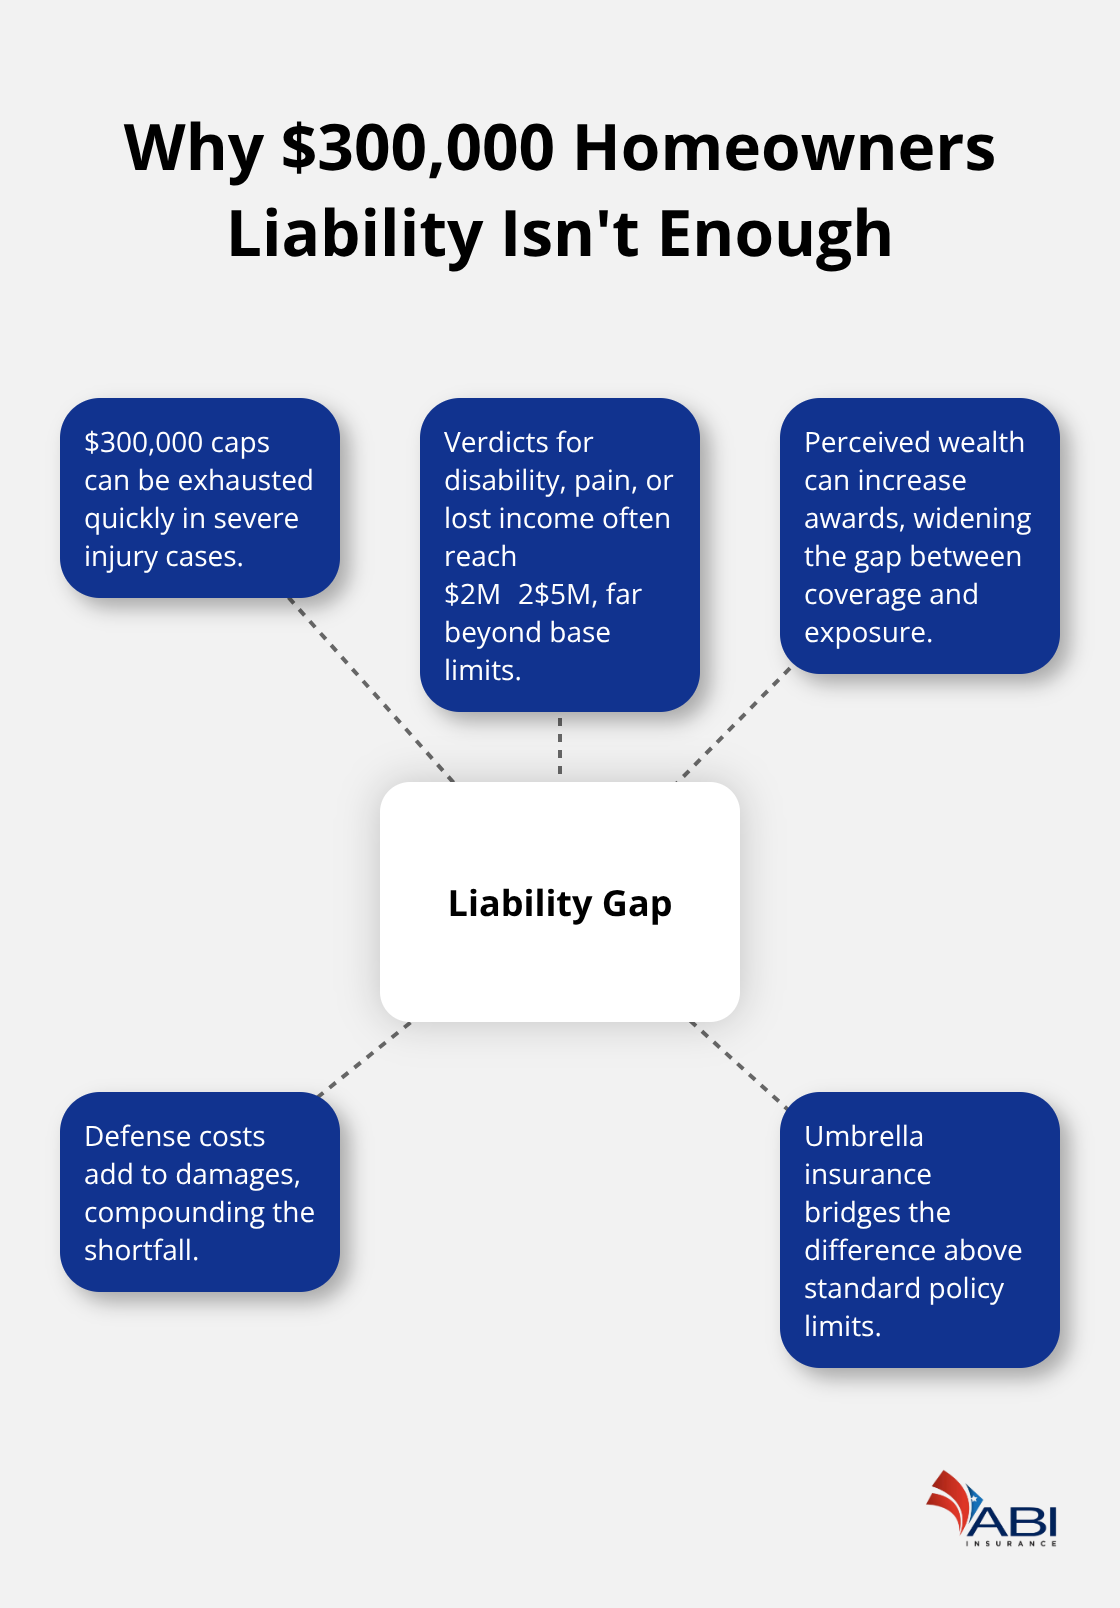
The gap between what your standard policies cover and what you actually owe is where financial devastation happens.
High net worth individuals in Portland face an additional problem: insurers underwrite standard homeowners policies based on typical risk profiles, not luxury exposure. A $1 million home with a guest house, pool, and frequent entertaining represents far more liability risk than the underwriting assumptions built into a $300,000 liability limit. Your standard policy treats your property the same way it treats a modest suburban home, even though your activities and assets create substantially different exposure.
Investment Properties Create Separate Exposures
Investment properties create liability exposures that your primary residence policy does not touch. Your primary residence policy does not extend to rental homes, vacation properties, or commercial real estate. Each property needs its own underlying coverage, and each carries its own liability limit. If a tenant at your rental property suffers a serious injury and wins a judgment exceeding your landlord policy limit, you personally absorb the difference.
The landlord liability exposure intensifies when you own multiple rental units or properties in different states. A single tenant claim can exhaust your coverage for that property, leaving you exposed on subsequent claims. Vacation homes present similar risks. A guest injured at your mountain cabin or beach house triggers liability that your primary residence policy ignores entirely.
Multiple Vehicles Multiply Your Auto Exposure
Wealthy households often own luxury cars, sports cars, or specialty vehicles worth $100,000 or more. Your auto policy likely carries $500,000 in liability limits if you’ve upgraded from Oregon’s legal minimums ($25,000 per person for bodily injury and $20,000 for property damage). A single at-fault accident involving a high-value vehicle can trigger a substantial claim for the other party’s injuries plus property damage. Your auto policy limit covers only that one vehicle, and if you own five cars, you have five separate exposures with five separate limits. The math fails quickly when one accident exhausts your coverage and leaves you liable for the remainder.
Standard Policies Ignore Your Actual Risk Profile
Standard policies treat all homeowners and all drivers the same way, regardless of net worth or asset complexity. Families with $3 million in home equity, $2 million in investments, and $1 million in rental property income operate under policies designed for middle-class households. Your liability exposure scales with your assets, your properties, and your activities. Hosting frequent events increases risk. Owning pools or trampolines creates attractive nuisance liability. Renting out property introduces tenant-related claims. Driving luxury vehicles attracts higher damage awards. Standard policies do not account for these realities.
Umbrella liability insurance exists precisely because standard policies fail at scale. Once you understand that a single lawsuit can exceed your policy limits by $1 million, $2 million, or more, the cost of umbrella coverage becomes trivial. The question shifts from whether you can afford umbrella insurance to whether you can afford to face a major liability claim without it. That question leads directly to understanding how much coverage you actually need.
Sizing Your Umbrella to Match Your Actual Exposure
Calculate Your Total Asset Exposure
Start with your total liquid and illiquid assets, then subtract what your current policies already cover. Add your home equity, investment accounts, retirement funds, rental property values, and any other significant assets. Most high-net-worth individuals in Portland underestimate this number on the first pass. A $2 million home, $1.5 million in investment accounts, $800,000 in rental property equity, and $600,000 in retirement savings totals $4.9 million in exposed assets. Your homeowners policy covers $300,000 in liability. Your auto policy covers $500,000. The gap between your coverage and your net worth is roughly $4.1 million, and that gap is exactly what umbrella insurance must fill.
Match Coverage Limits to Your Net Worth
According to the Insurance Information Institute, typical umbrella liability limits start at $1 million and extend to $5 million or higher for ultra-high net worth households. For Portland-area residents with $3 million to $5 million in net worth, $2 million to $3 million in umbrella coverage is standard. For those exceeding $5 million in assets, $5 million or more makes sense. This is not theoretical math. A jury verdict for permanent disability or chronic pain regularly reaches $2 million to $5 million depending on the plaintiff’s age, lost income potential, and the defendant’s perceived wealth. Courts and juries know your asset profile, and awards reflect it.
Understand Underlying Policy Requirements and Costs
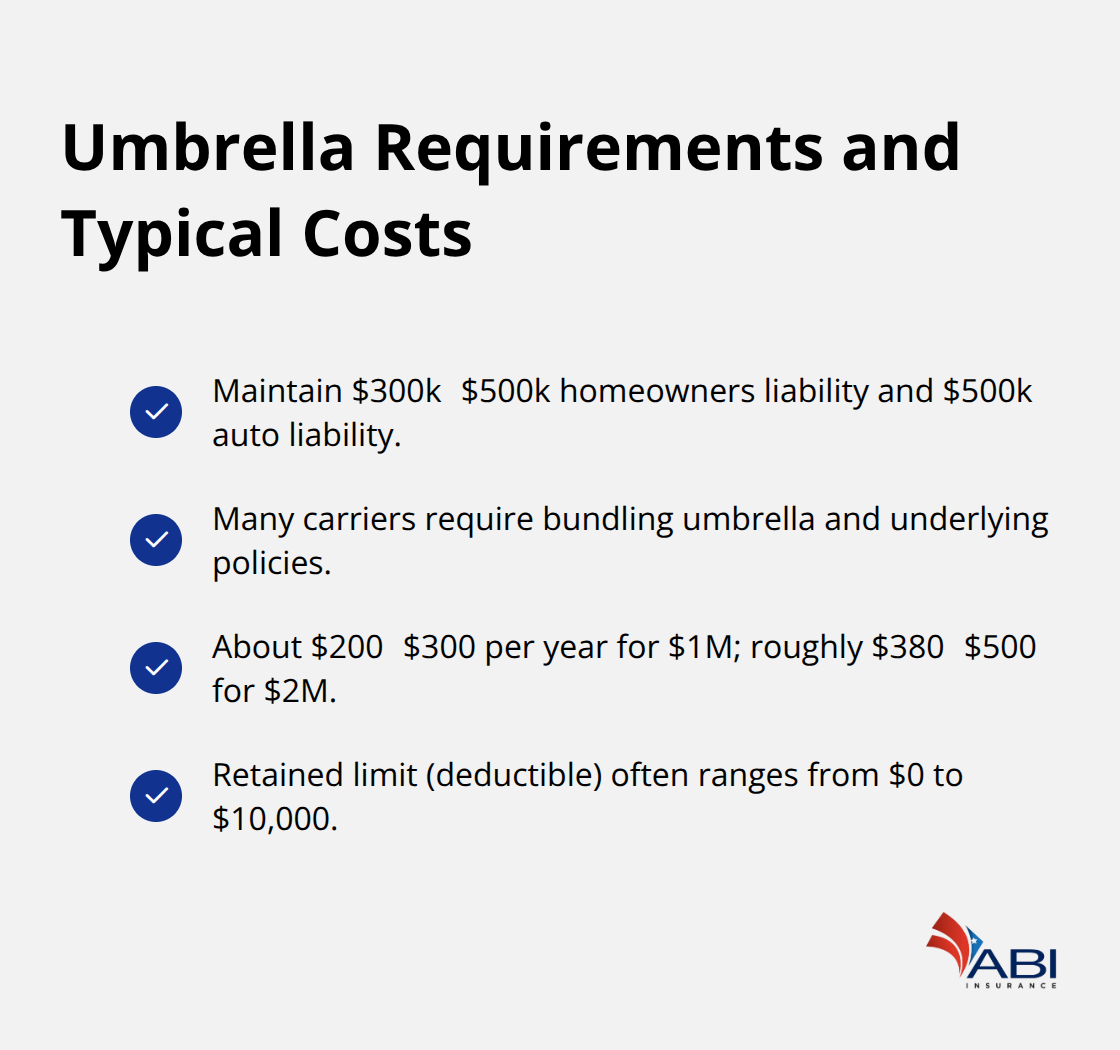
Your umbrella policy requires you to maintain minimum liability limits on underlying policies, typically $300,000 to $500,000 on homeowners and $500,000 on auto, according to the Insurance Information Institute. Many insurers also require you to purchase both your umbrella and underlying policies from the same carrier, which can limit your shopping flexibility but simplifies coordination. Typical umbrella coverage costs around $300 or more annually for $1 million in protection and roughly $400 or more for $2 million, making the expense negligible relative to the protection gained. The retained limit, or deductible, on your umbrella typically ranges from zero to $10,000, and you should understand exactly how this applies before you need it.
Work with Local Expertise on Portland-Area Risks
An agent familiar with your market knows whether your neighborhood’s liability profile, your property characteristics, and your activities justify higher coverage limits than standard recommendations suggest. Local expertise matters because Portland-area high net worth households face specific risks tied to owning multiple properties, rental income, and the region’s unique liability environment. An agent who has underwritten Portland-area families understands Oregon liability law, luxury asset concentration, and the exposure created by vacation homes or investment properties. ABI Insurance, a Beaverton-based independent agency with more than 40 years of experience, works with families across the Portland metro area to structure umbrella coverage that matches actual exposure rather than applying one-size-fits-all limits.
Final Thoughts
Your wealth demands protection that standard policies simply cannot provide. HNW umbrella insurance in Portland bridges the gap between what your homeowners and auto policies cover and what a serious lawsuit could cost you. A single liability claim exceeds your underlying policy limits by $1 million, $2 million, or more, and without umbrella coverage, you personally pay the difference.
The cost of umbrella coverage proves negligible compared to the financial devastation a major claim creates. Annual premiums for $2 million to $3 million in coverage typically range from $400 to $800, making this one of the most cost-effective risk management decisions you can make. More importantly, umbrella insurance covers your legal defense costs, which can reach $50,000 or more in complex cases. These expenses apply whether you win or lose, and they drain your assets while your case proceeds.
Proactive risk management means addressing your exposure before a claim forces you to act. Taking action now means working with an agent who understands your specific situation, your properties, your activities, and your actual net worth. Contact ABI Insurance to review your current coverage, calculate your true asset exposure, and determine the umbrella limits that make sense for your family.


 Small Business Cyber Liability: Essential Protections for Startups









