


Most homeowners assume their standard insurance policy covers earthquake damage. It doesn’t.
At ABI Insurance, we’ve seen firsthand how a single earthquake can wipe out a family’s financial security. Earthquake insurance for homeowners isn’t optional in high-risk areas. It’s the difference between rebuilding and losing everything.
What Your Homeowners Policy Actually Covers
The Standard Policy Gap
Your standard homeowners insurance policy covers fire, theft, wind, and hail damage. Homeowners, renters, and condo insurance policies do not cover earthquakes. This is the hard truth we communicate to homeowners every single day, and it’s the reason countless families face financial ruin after a seismic event. In California, the only exception is fire damage caused by an earthquake, which homeowners policies do cover. But structural damage, loss of personal property, and temporary housing costs from ground shaking? Those fall completely outside your standard policy.
This gap exists because earthquake risk is difficult to predict and potentially catastrophic, making it economically impossible for standard homeowners insurers to bundle it into regular coverage. If you live in the Portland metro area or anywhere across the Western U.S., you cannot assume you’re protected when the ground shakes.
Why Earthquakes Fall Outside Standard Coverage
Earthquake risk presents a unique challenge for insurers. Unlike fire or wind damage, seismic events can affect entire regions simultaneously, creating massive concentrated losses that standard homeowners policies cannot absorb. Insurers price standard coverage based on predictable, localized risks. Earthquakes violate that model entirely. The result: insurers exclude them from standard policies and require separate, specialized coverage to manage the exposure.
The Real Cost of Being Uninsured
A moderate earthquake can easily cause $100,000 to $500,000 or more in home damage, yet the average homeowner has zero coverage for this specific peril. The National Association of Insurance Commissioners emphasizes that even if you doubt your losses exceed your deductible, you must report earthquake damage to your insurer promptly because hidden structural damage often surfaces weeks or months after the initial event.
Consider this scenario: your home suffers $150,000 in earthquake damage, and you have no earthquake insurance. You become responsible for the entire amount unless you qualify for FEMA disaster assistance or federal disaster loans. Federal loans require repayment and come with strict eligibility criteria. Without earthquake insurance, your only realistic option is to fund repairs yourself, take on debt, or delay rebuilding indefinitely.
Your Protection in High-Risk Zones
In high-risk zones like the Pacific Northwest, where the Cascadia Subduction Zone and other faults pose genuine threats, earthquake insurance isn’t a luxury. It’s the only financial protection that actually covers the damage your home might sustain. The question isn’t whether you can afford earthquake insurance. The question is whether you can afford not to have it. Understanding what coverage options exist and how they work becomes your next critical step.
What Earthquake Insurance Actually Pays For
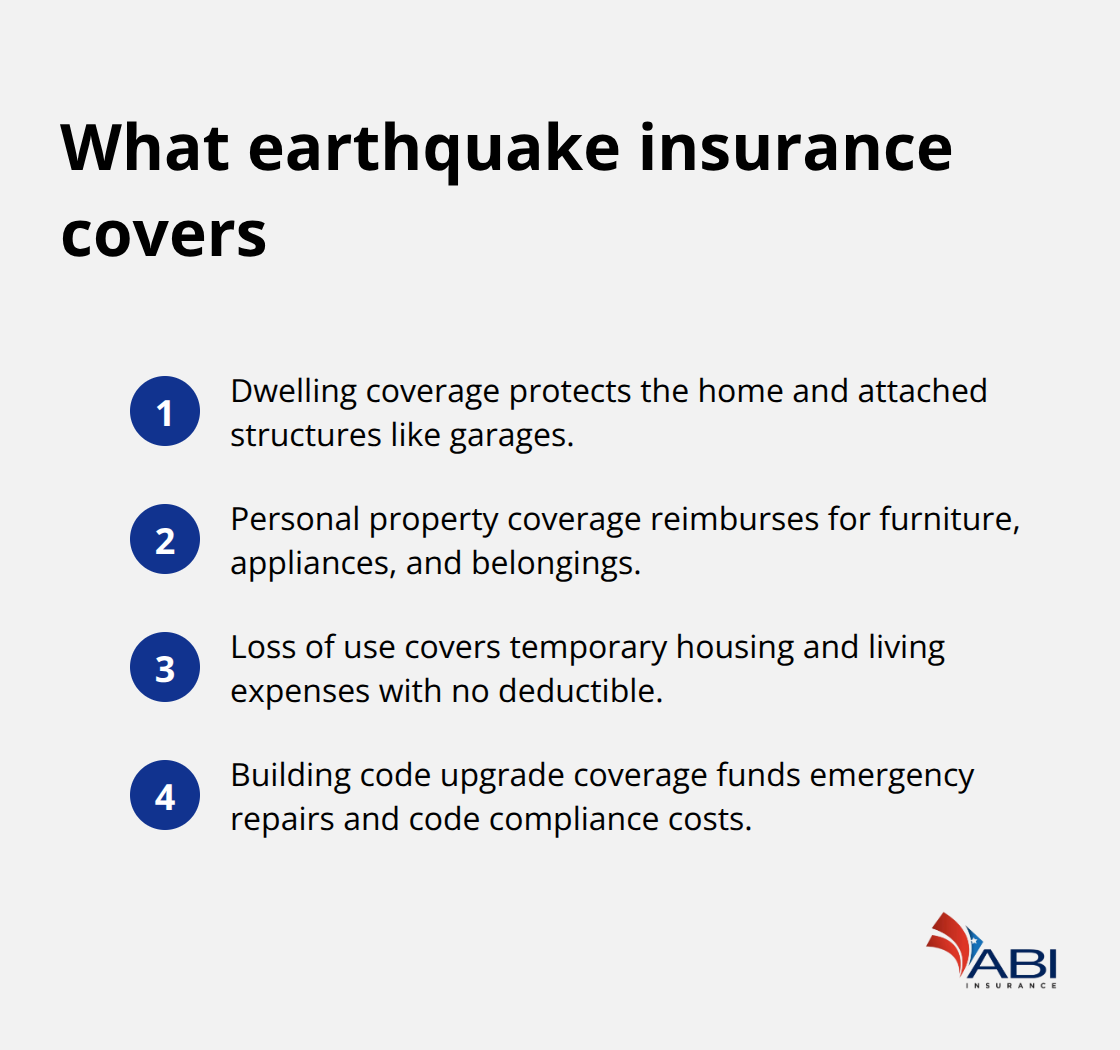
Earthquake insurance covers direct damage to your home’s structure and belongings caused by ground shaking, but the specifics matter enormously when you file a claim. The California Earthquake Authority, which insures most residential earthquake policies in California, breaks coverage into distinct parts: dwelling coverage for your house and attached structures like garages, personal property coverage for furniture and belongings inside your home, loss of use coverage for temporary housing and living expenses if your home becomes uninhabitable, and building code upgrade coverage to handle the added costs of meeting current construction standards during rebuilding. Dwelling coverage typically extends up to your homeowners policy limit, while personal property coverage starts at $5,000 and can increase to $25,000 or more depending on your needs. Loss of use coverage ranges from $1,500 to $100,000 with no deductible, which means you pay nothing to access this benefit. Building code upgrade coverage includes up to $1,500 for emergency repairs with no deductible, then additional limits up to $30,000 for code compliance costs.
What Stays Outside Your Coverage
Earthquake insurance excludes several important categories. Indirect damage, such as fire from burst gas lines or water damage from ruptured pipes, falls under your standard homeowners policy, not earthquake coverage. Landslides, ground settlement, floods, tsunamis, and damage from pre-existing structural problems remain entirely excluded. This distinction matters because you may assume earthquake coverage handles all earthquake-related losses, when in fact your standard policy and earthquake policy work together to cover different aspects of the same event.
How Deductibles Work Against You
Earthquake deductibles operate completely differently from standard homeowners deductibles. Instead of a fixed dollar amount like $1,000 or $1,500, earthquake deductibles are calculated as a percentage of your coverage limit, typically ranging from 2.5% and up. With a $200,000 dwelling limit and a 10% deductible, you pay $20,000 in damage before insurance pays anything.
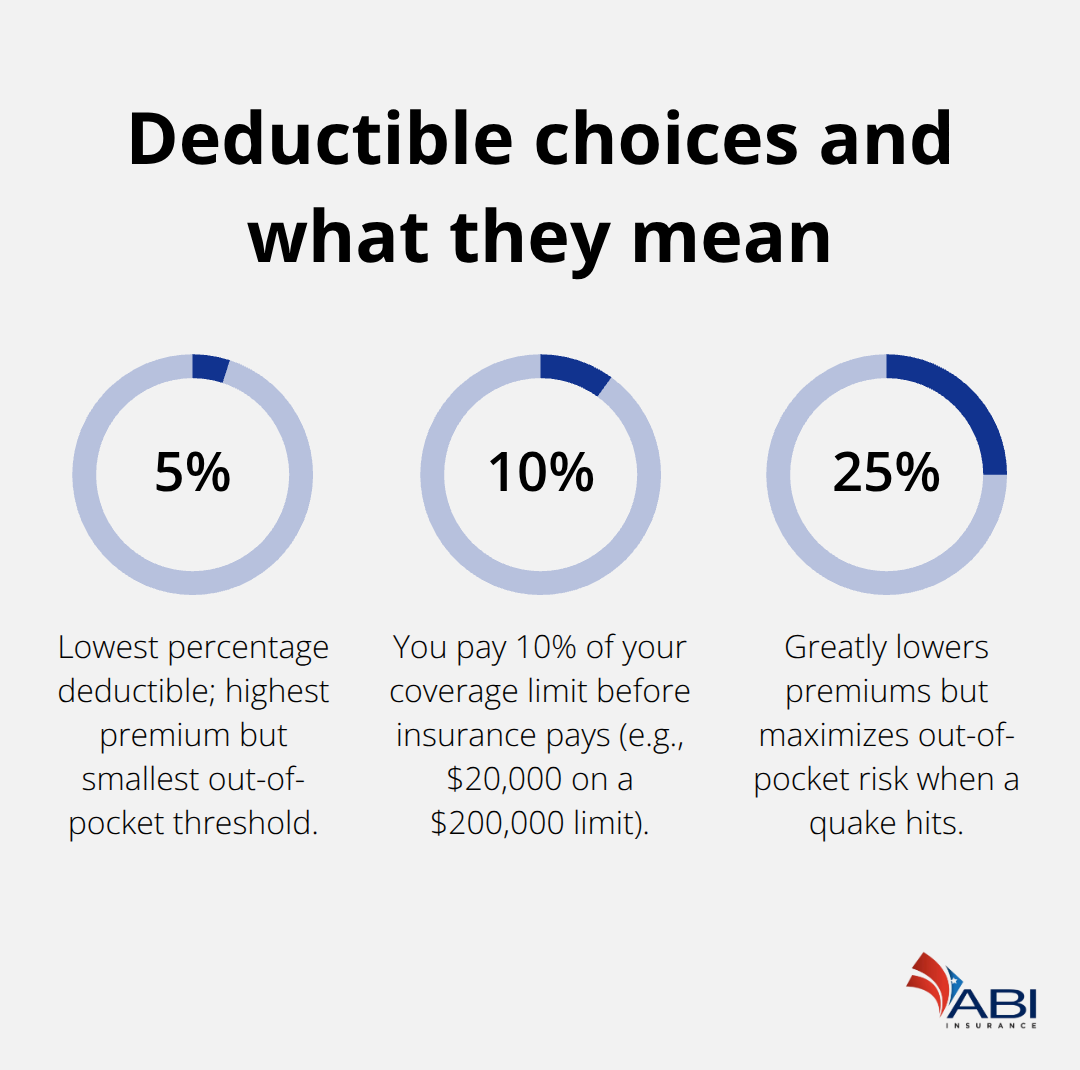
A moderate earthquake with $50,000 in damage leaves you paying $20,000 out of pocket, with insurance covering only $30,000. Older homes with certain foundation types or non-code-compliant construction face minimum deductibles of 15%, 20%, or even 25%, dramatically increasing your out-of-pocket exposure.
The timing of aftershocks creates additional financial risk. Most earthquakes occurring within 72 hours are treated as a single event with one deductible, but aftershocks more than 72 hours later trigger a second claim and a second deductible. This timing distinction can cost you thousands if a major quake is followed by significant aftershocks weeks later. Retrofitting your home, for example, bolting the foundation, bracing interior walls, securing water heaters, and installing automatic gas shut-offs can qualify you for premium discounts, offsetting some deductible burden through lower premiums.
What Your Premium Actually Reflects
Annual earthquake insurance premiums vary dramatically based on home age, construction type, soil conditions, proximity to fault lines, and your chosen deductible. A newer home in low-risk areas might cost $200 to $400 annually, while an older brick or masonry home in high-risk zones near active faults can exceed $1,500 to $2,000 per year.
Location matters most: homes in the Portland metro area face different risk profiles and the Cascadia Subduction Zone creates genuine exposure for Western U.S. homeowners. Construction type significantly impacts pricing. Wood-frame homes typically cost less to insure than unreinforced masonry or multi-story buildings. Sandy or soft soil increases premiums because ground shaking amplifies in these conditions. A home built before 1980 without seismic retrofitting pays substantially higher premiums than code-compliant newer construction.
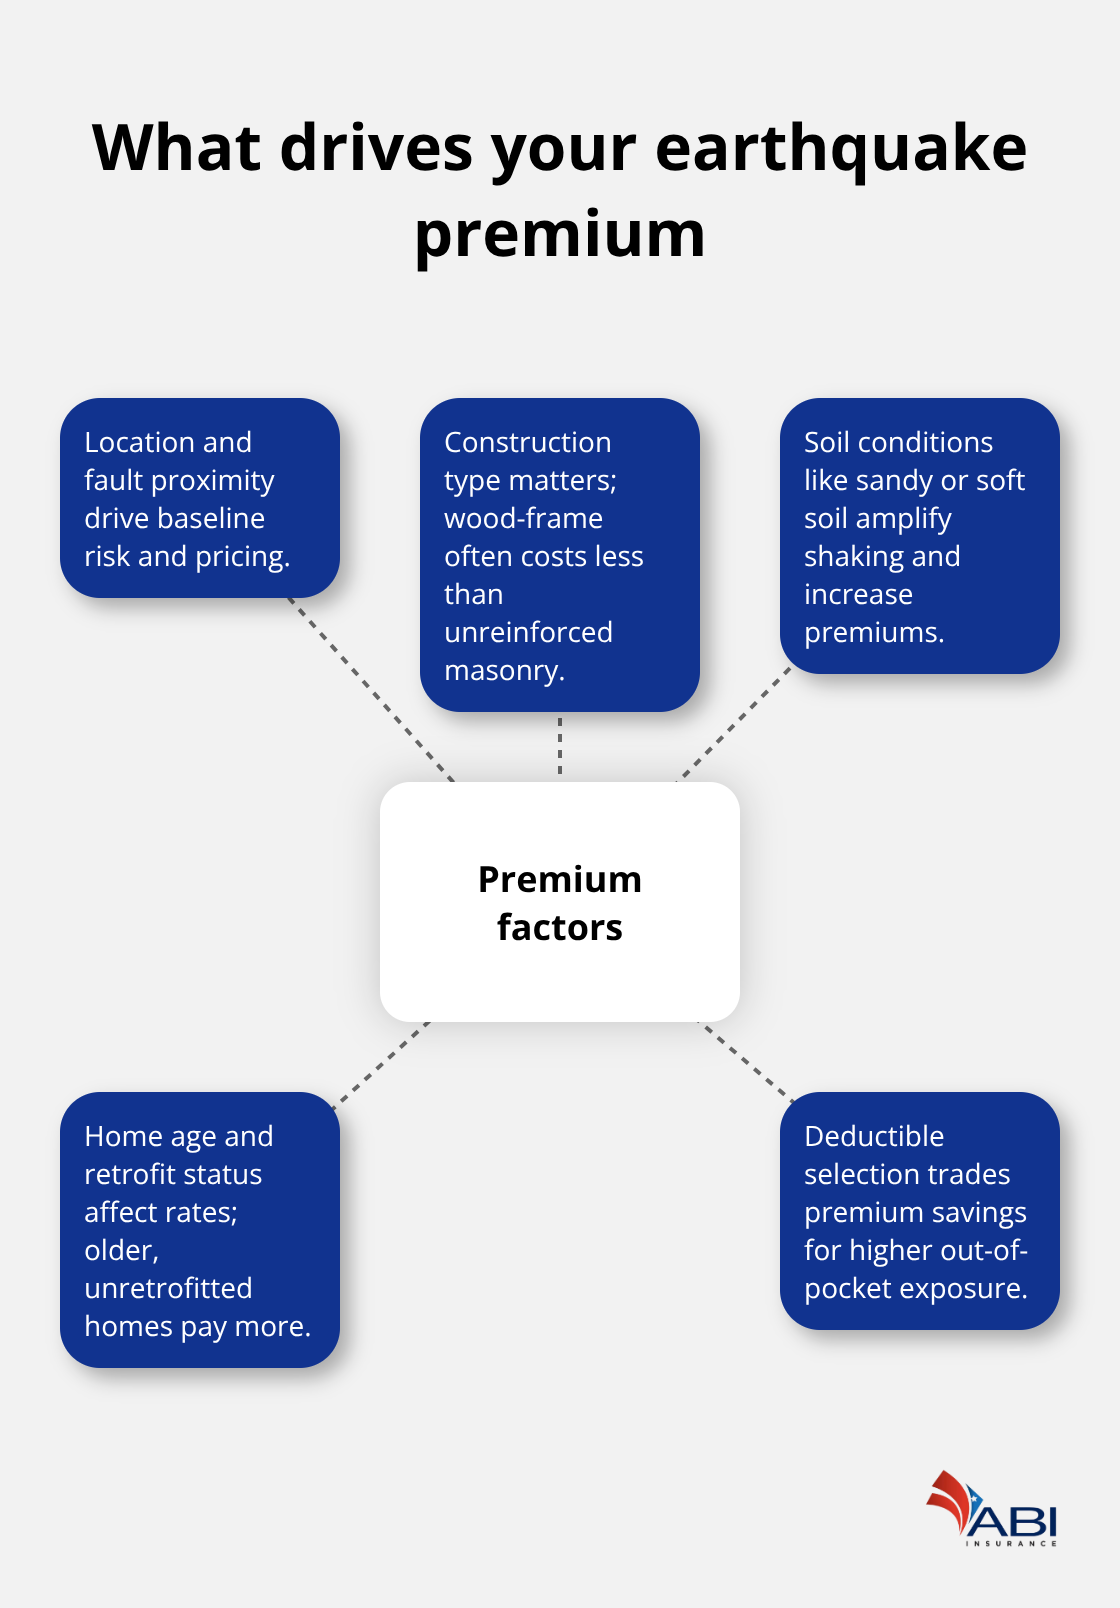
The deductible you select directly influences your premium: choosing 25% instead of 5% reduces your annual cost, but dramatically increases your financial exposure when a quake hits. Many homeowners incorrectly assume they cannot afford earthquake insurance, yet they’re actually choosing not to afford the financial catastrophe that follows an uninsured earthquake event. Understanding these costs and coverage limits sets the stage for the critical next step: selecting the right policy for your specific situation and risk profile.
Selecting the Right Policy for Your Situation
Calculate Your True Replacement Cost
Start with your home’s actual replacement cost, not its market value. Market value includes land; replacement cost covers only rebuilding the structure. A 2,000-square-foot home in the Portland metro area typically costs $250 or more per square foot to rebuild, translating to $350,000 or more in replacement costs. Your earthquake dwelling coverage should align closely with this number.
Underinsuring by $200,000 means you absorb that loss yourself after a quake, regardless of your policy limits. Many homeowners set earthquake limits equal to their homeowners dwelling limit, which often falls short of true replacement cost. Request a professional home inspection that addresses seismic vulnerability: foundation type, soil conditions, roof attachment, and chimney bracing. Older homes without foundation bolting face higher premiums and deductible minimums, sometimes capped at 15% to 25% rather than 5%.
Evaluate Retrofit Opportunities and Costs
Retrofitting costs can typically start at $3,000 and go up, but can reduce premiums by up to 25%, paying for itself within three to five years while dramatically improving structural resilience. Foundation bolting, interior wall bracing, water heater securing, and automatic gas shut-off installation all strengthen your home’s ability to withstand seismic events.
Compare Quotes Across Multiple Insurers
When selecting a policy, confirm whether your deductibles apply separately to dwelling and contents, as this affects how much you’ll pay out-of-pocket after a claim. Compare total annual cost across 5%, 10%, 15%, 20%, and 25% deductible options.
A $500,000 dwelling limit with a 10% deductible costs significantly less than 15%, but your out-of-pocket exposure jumps from $50,000 to $75,000 after a moderate quake. Factor in your liquid savings: if you have $40,000 in emergency reserves, a 10% deductible on $400,000 coverage ($40,000) aligns with your actual financial capacity. Deductibles above your savings create unmanageable gaps.
Select Coverage Limits That Match Your Needs
Request personal property limits that reflect your actual contents. Most policies start at $5,000; upgrading to $15,000 or $25,000 typically adds $50 or more annually but protects against catastrophic losses from furniture, appliances, and electronics. Loss of use coverage with no deductible should never be skipped. It covers hotel stays, meals, and temporary housing during repairs, with limits from $1,500 to $100,000. We recommend taking the highest limits offered by your carrier.
Review Exclusions and Document Your Home
Read policy exclusions carefully: confirm what indirect damage coverage your standard homeowners policy actually provides, verify whether your soil type triggers exclusions, and understand that floods and tsunamis remain excluded even if earthquake-triggered. Document your home’s current condition with photos and video before purchasing coverage, establishing a baseline for future claims. This documentation proves invaluable when you file a claim and need to demonstrate pre-existing conditions versus earthquake damage.
Final Thoughts
Earthquake insurance for homeowners isn’t a decision you can postpone. The ground beneath your home will shake again. The only unknowns are when and how severely. Without earthquake coverage, you’re gambling with your family’s financial security and your ability to rebuild.
We at ABI Insurance have spent over 40 years helping families across the Portland metro area and the Western U.S. understand their true exposure to seismic risk. The homeowners who sleep soundly aren’t those who hope earthquakes won’t happen. They’re the ones who calculated their replacement costs, selected appropriate deductibles, and locked in coverage before the next major event strikes. Your next step is straightforward: contact your insurance agent.
Request quotes at multiple deductible levels and compare total annual premiums alongside your out-of-pocket exposure. If retrofit opportunities exist, factor those costs against potential premium discounts. Contact ABI Insurance today to discuss your situation and receive concrete quotes for earthquake insurance for homeowners throughout the Western U.S.


 Travel Smarts for Your Money and Identity









