
Oregon clinicians face real threats to their practices every day. Malpractice claims, regulatory scrutiny, and financial exposure can derail even the most careful practitioners.
At ABI Insurance, we’ve helped countless healthcare providers across Oregon implement medical professional liability solutions that work. This guide walks you through the coverage options, risk management strategies, and protections your practice needs to operate with confidence.
Liability Risks That Threaten Oregon Clinicians
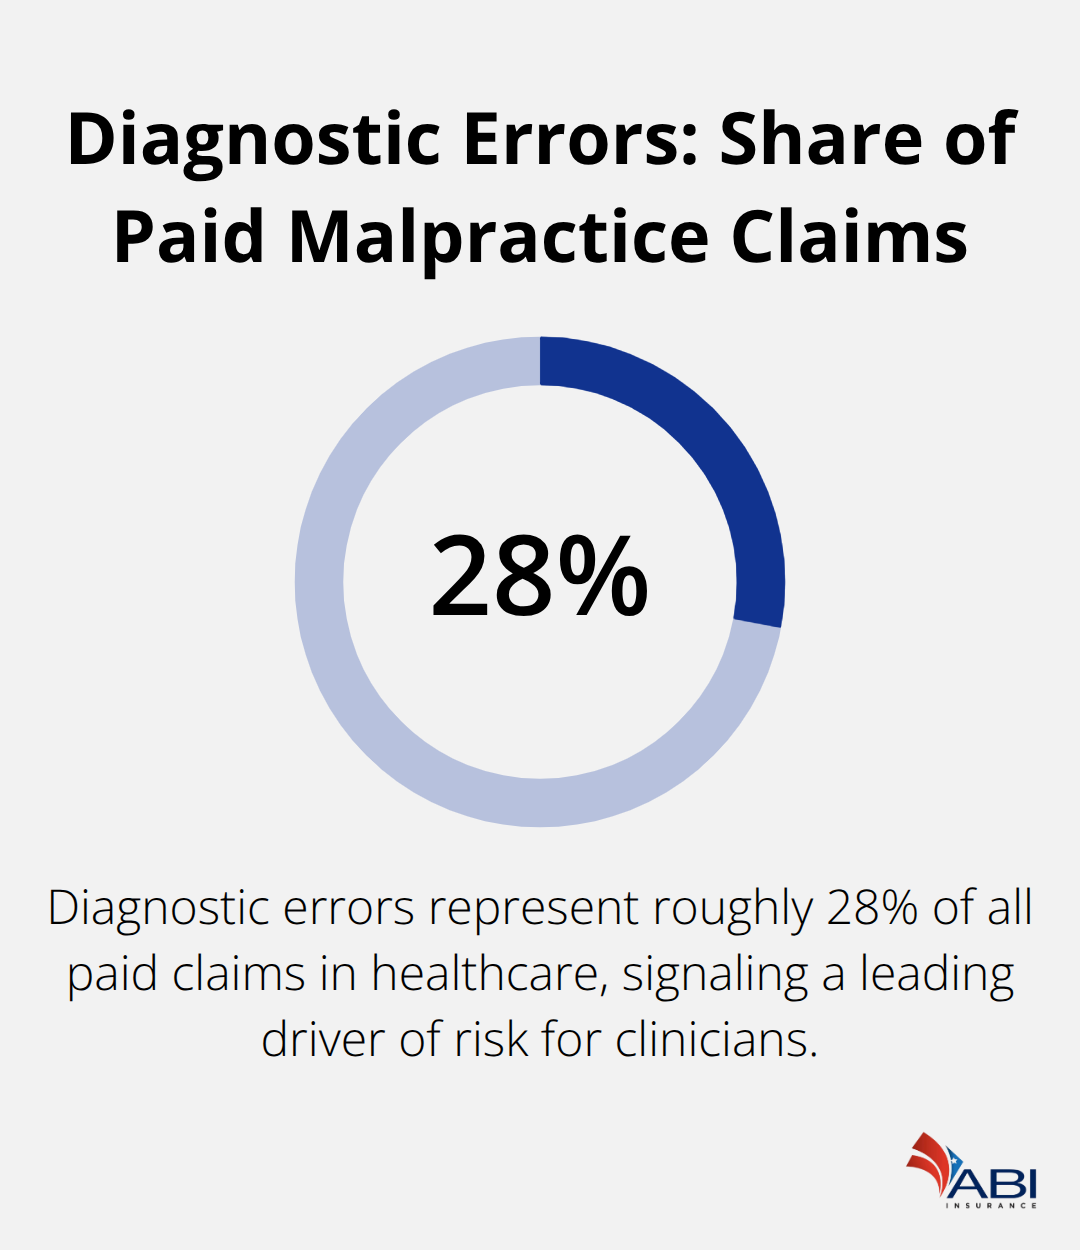
Oregon healthcare providers face specific liability exposures that differ from other states. Diagnostic errors, surgical complications, medication mistakes, and missed diagnoses are the largest categories of claims filed against Oregon clinicians. According to the National Practitioner Data Bank, which tracks all reported malpractice payments, diagnostic errors account for roughly 28% of all paid healthcare claims.
For Oregon specifically, claims involving delayed cancer diagnosis, misread imaging results, and missed sepsis cases appear with troubling regularity. These aren’t rare edge cases; they’re predictable patterns that affect practices across specialties.
Obstetrics carries the highest average settlement amounts, with birth injury claims averaging $500,000 or more. Emergency medicine and primary care generate high claim frequency because of the volume of patients seen and the time constraints clinicians work under. Orthopedic surgery and anesthesia also rank high in both claim frequency and severity.
The Financial Reality of Malpractice Defense
The financial exposure is staggering. The average cost to defend a medical malpractice claim runs $100,000 to $150,000 even before any settlement or judgment. When claims proceed to trial, defense costs often exceed $200,000.
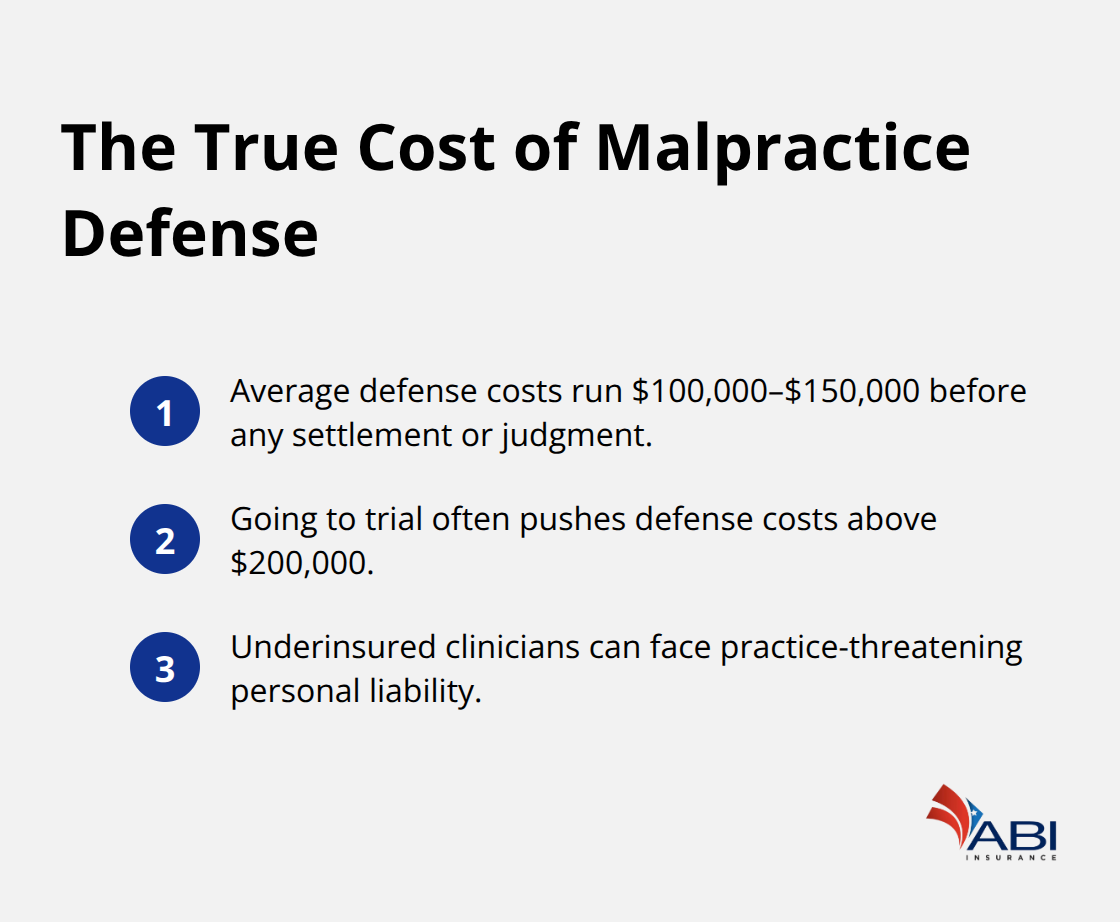
Oregon clinicians who lack proper coverage face direct liability for these costs, which can bankrupt a solo practice or partnership.
Beyond individual claims, Oregon enforces strict regulatory oversight through the Oregon Medical Board and the Oregon Board of Nursing. Licensing complaints, disciplinary actions, and regulatory investigations create additional financial and reputational exposure that standard professional liability policies may not adequately address. Regulatory defense costs stack on top of malpractice defense costs, creating a dual financial threat that many clinicians underestimate.
Why Tail Coverage Matters More Than Clinicians Think
Most Oregon clinicians operate under claims-made policies, which only cover incidents reported while the policy is active. This creates a critical gap when clinicians retire, sell practices, or change coverage. A patient can file a claim five years after treatment ends, but if your claims-made policy has lapsed, you have zero coverage.
Tail coverage, also called run-off coverage, extends reporting periods for claims arising from past work. Without tail coverage, retiring clinicians or those changing insurers face massive, unprotected liability. Tail coverage typically runs 150% to 200% of your annual premium, depending on your specialty and claims history. This expense shocks many clinicians, but it’s genuinely non-negotiable. Oregon regulators expect clinicians to maintain tail coverage or maintain evidence of other adequate protection when leaving practice.
Regulatory Compliance and Board Investigations
Oregon’s regulatory environment demands meticulous documentation, informed consent procedures, and compliance with specific state statutes governing medical practice. Violations trigger board investigations independently of any patient lawsuit. These investigations consume time, generate legal fees, and damage professional reputation.
Clinicians need coverage that addresses regulatory defense separately from malpractice defense because these represent distinct legal battles with different costs and outcomes — understanding what your policy covers and what it does not determines whether you can weather a regulatory storm or face financial devastation.
Coverage Options for Medical Professionals
Professional liability insurance for Oregon clinicians comes in fundamentally different structures, and selecting the wrong one leaves you exposed when you need protection most. Claims-made policies dominate the medical liability market because they cost less upfront than occurrence policies. A claims-made policy covers incidents only if both the incident and the claim report happen while your policy is active. This creates a dangerous trap: a patient treated in 2024 can file a claim in 2029, but if your claims-made policy lapsed in 2025, that claim receives zero coverage. Occurrence policies work differently. They cover any incident that happened during the policy period, regardless of when the claim arrives. Occurrence coverage costs 40% to 60% more annually than claims-made policies, which explains why most Oregon clinicians use claims-made plans. However, occurrence policies eliminate the tail coverage problem and provide genuine peace of mind during career transitions.
Understanding Tail Coverage and Its True Cost
Tail coverage extends your reporting period after you leave a practice, retire, or switch insurers. Tail premiums typically run between 1.5 to 2 times your current annual premium, depending on specialty and claims history. Emergency medicine and obstetrics clinicians face the highest tail costs because these specialties generate frequent claims. A family medicine clinician paying $3,000 annually for claims-made coverage might face a $4,500 to $9,000 tail premium when retiring. This expense catches most clinicians off guard because they don’t budget for it during their careers. Some practices negotiate tail coverage as part of sale agreements, where the buyer assumes tail responsibility. Others purchase extended tail policies that cover claims reported within specific time windows after departure. Oregon regulators expect documented tail coverage or equivalent protection before you leave practice; failing to secure it creates regulatory exposure independent of any patient claim.
Regulatory Defense Coverage You Cannot Ignore
Standard professional liability policies cover defense costs and settlements for patient claims, but they rarely cover regulatory defense, board investigations, or licensing defense. Oregon Board of Nursing investigations and Oregon Medical Board disciplinary actions require separate legal representation and generate distinct costs. Many clinicians discover too late that their malpractice policy excludes regulatory defense entirely. Specialized medical professional policies from carriers experienced with Oregon’s regulatory environment include coverage for board investigations, licensing defense, and regulatory fines. These protections matter because regulatory battles consume significant resources and damage professional reputation independent of any patient lawsuit.
Additional Protections for Modern Practice Settings
Standard coverage addresses traditional office-based patient care, but modern clinicians practice across multiple settings and modalities. Telehealth incidents, independent contractor arrangements across multiple facilities, and electronic patient data storage create exposures that standard policies may not address. Clinicians working in high-risk specialties should verify that their policy covers all procedures and settings where they practice.
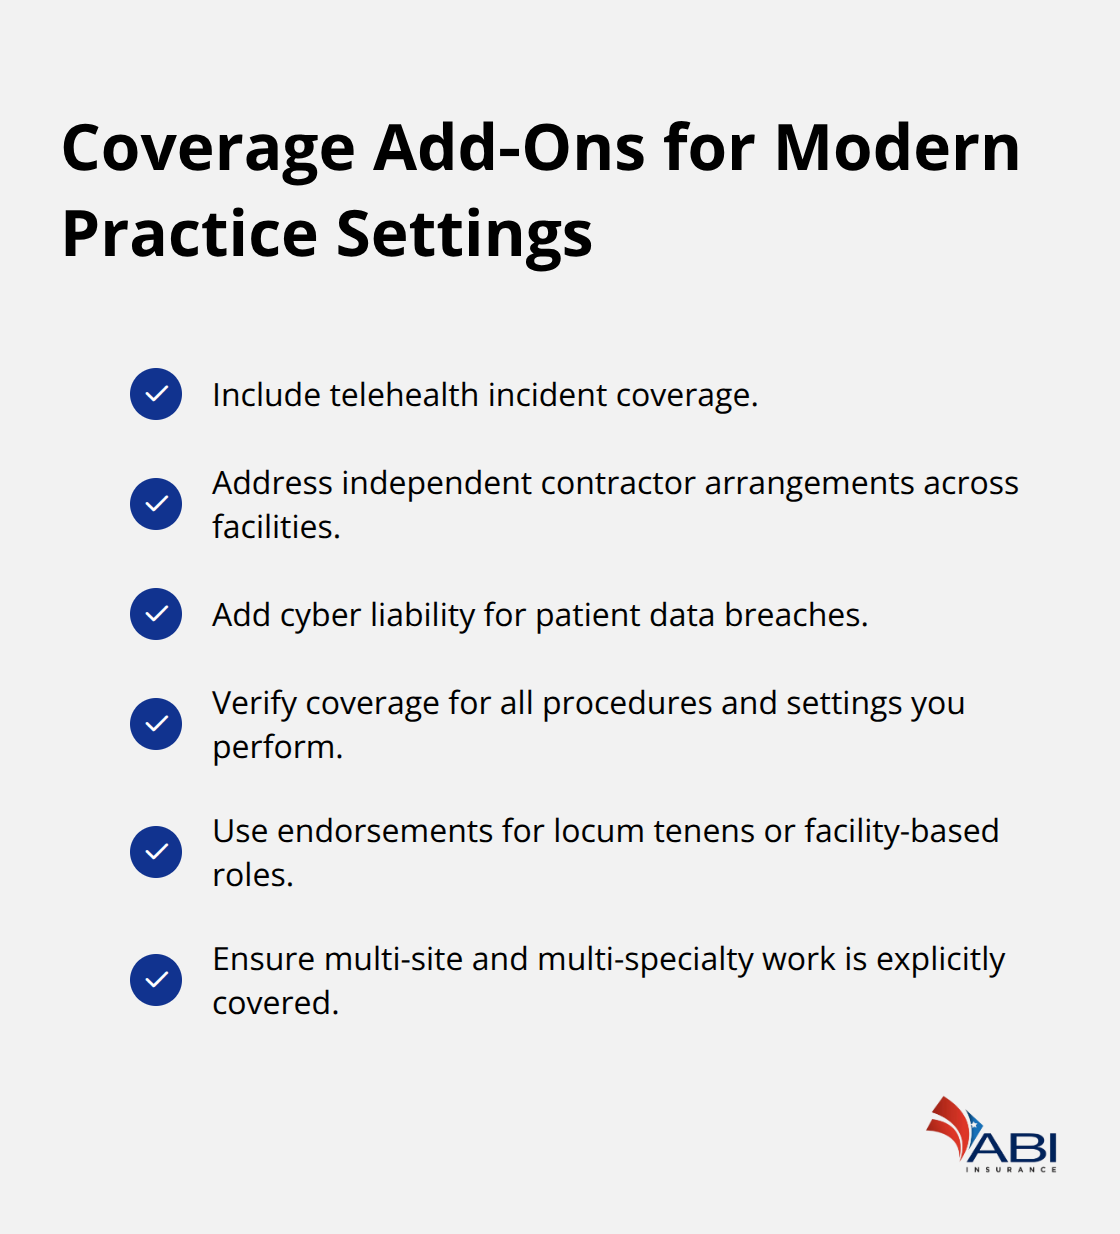
Coverage for cyber liability protects your practice if patient data breaches occur, which represents a growing regulatory concern in Oregon. Specialized endorsements for specific practice arrangements (such as locum tenens work or facility-based positions) prevent coverage gaps that emerge when clinicians work outside traditional employment structures.
Selecting Coverage That Matches Your Practice Reality
Your coverage selection depends on your specialty, career stage, and practice structure. Clinicians planning to practice for many more years might accept claims-made policies and budget for tail coverage at retirement. Those nearing career transitions should evaluate occurrence policies despite higher premiums, as peace of mind justifies the cost. Clinicians working across multiple settings or specialties need policies that explicitly cover all your actual practice activities, not just primary work settings. The right coverage structure protects your assets, your license, and your professional reputation, making this decision one of the most important risk management choices you make.
Risk Management Strategies That Protect Your Practice
Documentation Standards That Win Cases
Documentation determines whether you win or lose malpractice cases in Oregon. Courts assume that if something isn’t documented, it didn’t happen. A clinician with perfect clinical judgment but sloppy records loses to a clinician with average judgment but meticulous documentation every single time. Oregon courts follow this principle strictly, which means your chart becomes your defense when claims arise.
Most Oregon practices struggle with inconsistent documentation standards across staff members. One nurse charts detailed patient interactions while another writes vague notes that raise red flags during discovery. This inconsistency signals to plaintiff attorneys that your practice lacks systematic quality control, which damages credibility throughout the case.
Establish a single documentation standard for your entire team and audit charts weekly, not annually. Specifically, document the patient’s chief complaint, your clinical reasoning for each decision, what you ruled out and why, any patient refusal of recommended treatment, and follow-up instructions given to the patient. Include timestamps for all entries and never backdate notes. The Oregon Medical Board investigates backdated entries aggressively because they suggest concealment.
Documentation standards for medical malpractice defense in Oregon require proof that the provider failed to meet the standard of care ordinarily used by providers in the same field. When documentation quality improves across your practice, malpractice insurers often reduce your premiums because your risk profile improves measurably. Many Oregon clinicians resist detailed documentation because it feels time-consuming, but it saves time during depositions and trials when you can point to specific chart entries that prove your decision-making was sound.
Patient Communication That Prevents Litigation
Patient communication and informed consent represent your second line of defense against claims. Patients sue when they feel dismissed, unheard, or surprised by outcomes. A patient who experiences a complication but felt heard and informed throughout treatment rarely pursues litigation. Conversely, a patient with a minor complication who felt rushed or uninformed becomes a plaintiff.
Document every conversation about risks, benefits, and alternatives before procedures or treatments. Use plain language, not medical jargon, and verify that patients understand what you explained. Ask patients to explain back what they understood before they sign consent forms. Staff training on communication protocols prevents the dismissive comments that trigger patient anger and subsequent claims.
Teach your team that how you deliver bad news matters as much as the news itself. Oregon clinicians who implement structured communication training see measurable reductions in complaint rates within six months.
Quality Assurance Protocols That Identify Problems Early
Quality assurance protocols should include regular chart audits, case review meetings where staff discuss near-misses and complications, and annual competency assessments for all clinical staff. These protocols aren’t bureaucratic busywork. They identify system failures before they become patient injuries.
A practice that catches its own errors through internal review demonstrates due diligence that protects you during regulatory investigations and malpractice defense. When your team reviews cases systematically (rather than waiting for complaints to arrive), you spot patterns that individual clinicians might miss. This proactive approach reduces both claim frequency and severity across your practice.
Final Thoughts
Your professional liability insurance forms the foundation of your practice protection, but only if you select a partner who understands Oregon’s specific regulatory environment and the real risks you face daily. The wrong carrier leaves coverage gaps when you need protection. The right partner anticipates your needs, responds quickly to claims, and provides guidance that prevents problems before they escalate. When evaluating medical professional liability solutions, prioritize carriers with deep experience in Oregon healthcare who understand Oregon Board of Nursing enforcement patterns, Oregon Medical Board investigation procedures, and the specific claim patterns that affect your specialty.
We at ABI Insurance have spent more than 40 years serving Oregon healthcare providers with personalized medical professional liability coverage that matches your actual practice, not generic templates that leave you exposed. Our team understands the Portland metro area’s healthcare landscape and the unique pressures clinicians face across the Western U.S., and our claims support team responds rapidly when incidents occur. Our underwriters work with you to identify coverage gaps before they become problems and structure policies that include claims-made and occurrence options, transparent tail coverage pricing, and regulatory defense coverage as standard components.
Start by reviewing your current coverage against the standards discussed throughout this guide and identify any gaps in tail coverage, regulatory defense, or practice setting coverage. Contact ABI Insurance to discuss medical professional liability solutions tailored to your practice, and verify your policy covers all settings where you practice, including telehealth and facility-based work.


 How Do You Prepare for a Natural Disaster or Storm When You Have a Pet?









